 Phoenix Tax Consultant™ September 13, 2026
Quick answer | விரைவான பதில்
Tax audit under section 44AB is required for AY 2026-27 when business turnover exceeds ₹1 crore (₹10 crore if cash receipts and cash payments are each within 5%), or professional receipts exceed ₹50 lakh (₹75 lakh for presumptive 44ADA cases with limited cash). The audit report in Form 3CA/3CB-3CD was due on 21 October 2026 (extended) and the ITR on 21 November 2026. Missing it attracts a penalty of 0.5% of turnover, up to ₹1.5 lakh (section 271B).
AY 2026-27-க்கு, வியாபார வருவாய் ₹1 கோடியைத் தாண்டினால் (ரொக்க வரவு, செலவு 5%-க்குள் இருந்தால் ₹10 கோடி), அல்லது தொழில்முறை வருவாய் ₹50 லட்சத்தைத் தாண்டினால் பிரிவு 44AB-ன் கீழ் tax audit கட்டாயம். Audit report கடைசி நாள் 21 அக்டோபர் 2026, ITR 21 நவம்பர் 2026 (நீட்டிப்பு). தவறினால் வருவாயில் 0.5%, அதிகபட்சம் ₹1.5 லட்சம் அபராதம் (271B).
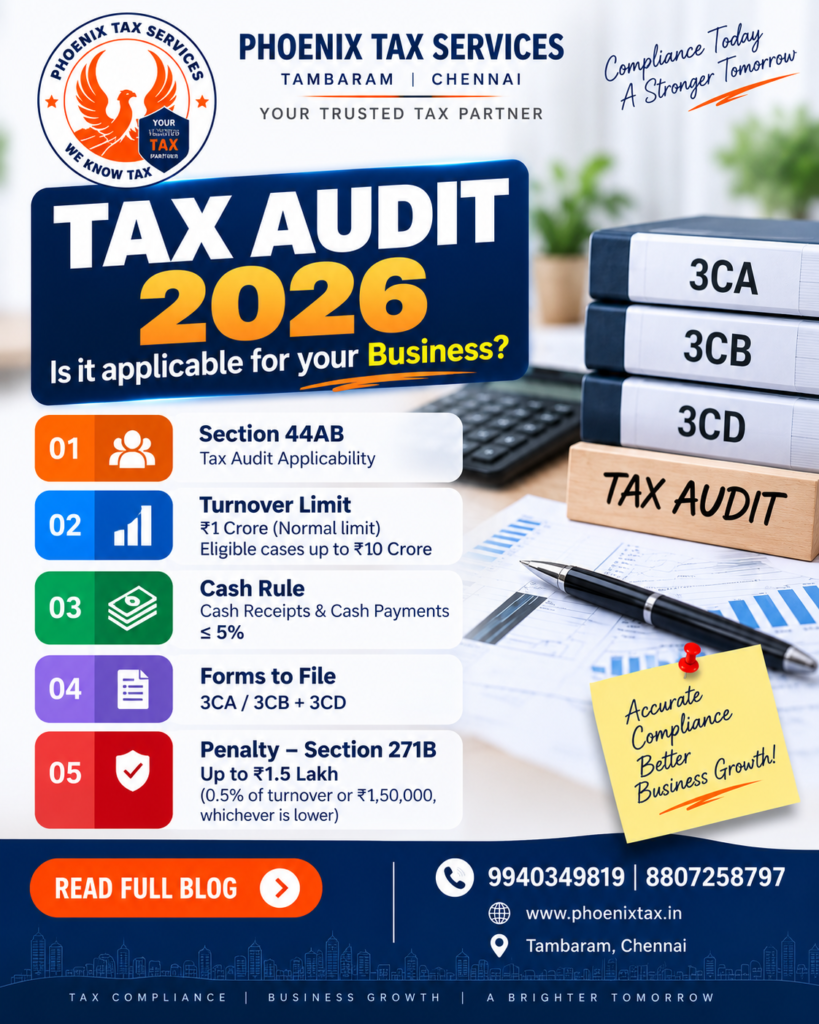
Tax Audit AY 2026-27 – Section 44AB applicability, 3CB/3CD report, due date and penalty guide.
Business பண்ணுற எல்லாருக்கும் Tax Audit கட்டாயம் கிடையாது. ஆனால் உங்கள் Turnover, Cash Receipts, Cash Payments, Profession மற்றும் Presumptive Taxation eligibility அடிப்படையில் Tax Audit applicable ஆகலாம்.
FY 2025-26 / AY 2026-27-க்கு Tax Audit applicability இன்னும் Income-tax Act, 1961 – Section 44AB அடிப்படையில்தான் பார்க்கப்படுகிறது. Income Tax Department-ன் தற்போதைய AY 2026-27 guidance இதைத் தெளிவாக உறுதிப்படுத்துகிறது.
🔍 யார் TAX AUDIT பண்ணணும்?
🏢 BUSINESS
பொதுவாக Business-ன் Total Sales / Turnover / Gross Receipts ₹1 Crore-ஐ தாண்டினால், Section 44AB கீழ் Tax Audit applicable.
ஆனால் முக்கியமான Digital Transaction Benefit இருக்கு 👇
Cash Receipts ≤ 5% AND Cash Payments ≤ 5% என்றால் Tax Audit turnover threshold ₹10 Crore வரை உயர்கிறது.
அதாவது ₹1 Crore தாண்டிய உடனே எல்லா business-க்கும் audit என்று முடிவு செய்யக்கூடாது. Cash receipt/payment condition-ஐ கண்டிப்பாக check செய்ய வேண்டும். AY 2026-27 official forms/guidance-லும் ₹1 crore–₹10 crore range மற்றும் 5% cash test explicitly இடம்பெற்றுள்ளது.
Example: Turnover ₹1.30 Crore; Cash Receipts NIL; Cash Payments NIL என்றால், turnover மட்டும் வைத்து Tax Audit compulsory என்று சொல்ல முடியாது. ₹10 Crore enhanced limit condition applicable ஆகுமா என்பதை முழு transaction pattern உடன் பார்க்க வேண்டும்.
👨⚕️ PROFESSIONALS
Profession-ல் Gross Receipts ₹50 Lakhs-ஐ தாண்டினால், Section 44AB tax audit requirement வரலாம். Presumptive taxation provisions applicable என்றால் 44ADA conditions-யும் தனியாக check செய்ய வேண்டும்.
⚠️ PRESUMPTIVE TAXATION CASES
44AD / 44ADA / 44AE / 44BB போன்ற presumptive provisions-ல் prescribed conditions satisfy செய்யாமல் lower profit/income declare செய்யும் சில cases-ல்கூட Tax Audit applicable ஆகலாம்.
அதனால் “Turnover ₹1 Crore கீழேதானே; Audit இல்லை” என்று turnover மட்டும் பார்த்து முடிவு செய்யக்கூடாது.
📑 TAX AUDIT எந்த FORM?
AY 2026-27க்கு existing forms தான்:
Form 3CA + Form 3CD — Accounts ஏற்கனவே Companies Act போன்ற வேறு சட்டத்தின் கீழ் audit செய்யப்பட வேண்டியவர்களுக்கு.
Form 3CB + Form 3CD — வேறு சட்டத்தின் கீழ் statutory audit requirement இல்லாமல் Section 44AB Tax Audit applicable ஆகிறவர்களுக்கு.
Income Tax Department AY 2026-27க்கு இந்த forms தொடர்வதை உறுதிப்படுத்தியுள்ளது.
📅 TAX AUDIT DEADLINE — AY 2026-27
🔥 Normal Tax Audit Cases: 30 SEPTEMBER 2026
Tax Audit applicable taxpayers-ன் ITR due date பொதுவாக 31 October 2026; அதற்கு ஒரு மாதத்திற்கு முன்பாக Tax Audit Report furnish செய்யப்படுகிறது.
Transfer Pricing cases-க்கு வேறு timeline பொருந்தும்; Income Tax Department guidance-ல் audit report date 31 October 2026 என்றும் corresponding ITR due date 30 November 2026 என்றும் குறிப்பிடப்பட்டுள்ளது.
❌ TAX AUDIT பண்ண வேண்டியது இருந்தும் பண்ணவில்லை என்றால்?
இதுதான் முக்கியம்.
Section 271B கீழ் penalty:
0.5% of Total Sales / Turnover / Gross Receipts
OR
₹1,50,000
👉 இதில் எது குறைவோ அது penalty ஆக விதிக்கப்படலாம்.
Income Tax Department-ன் current penalty guidance இதை உறுதிப்படுத்துகிறது. Reasonable cause போன்ற statutory relief facts-ஐப் பொறுத்து தனியாக பரிசீலிக்கப்படலாம்.
✅ TAX AUDIT பண்ணுவதால் என்ன BENEFIT?
Tax Audit-ன் நோக்கம் “வரி குறைப்பது” மட்டும் அல்ல.
Books of Accounts, Turnover, Expenses, TDS-related reporting, depreciation, statutory dues மற்றும் Income Tax Act-க்கு தேவையான பல disclosures சரியாக report செய்யப்பட்டுள்ளதா என்பதை structured முறையில் verify/report செய்ய உதவுகிறது.
இதனால் accurate financial reporting, correct tax computation, compliance discipline மற்றும் ITR filing consistency மேம்படும்.
⚠️ ஆனால் “Tax Audit செய்தால் notice வராது” என்று guarantee செய்ய முடியாது. அது தவறான claim.
🔥 INCOME TAX AUDIT vs GST AUDIT — இரண்டும் SAME இல்லை!
இதில் நிறைய Business Owners confuse ஆகிறார்கள்.
Income Tax: FY 2025-26 / AY 2026-27 Tax Audit → Section 44AB, Income-tax Act, 1961.
GST: பழைய mandatory CA/CMA GST Audit mechanism தற்போது அதே வடிவில் இல்லை. 01-08-2021 முதல், applicable taxpayers-க்கு Section 44 of CGST Act read with Rule 80 கீழ் self-certified GSTR-9C reconciliation statement framework உள்ளது.
Aggregate Turnover ₹5 Crore-ஐ தாண்டினால், applicable cases-ல் GSTR-9C self-certified reconciliation statement annual return உடன் furnish செய்யப்படுகிறது; prescribed annual-return timeline பொதுவாக following financial year 31 December.
👉 எனவே Income Tax Tax Audit threshold-ஐ GST ₹5 Crore threshold-உடன் mix பண்ணக்கூடாது.
⚡ BUSINESS OWNERS — இந்த 5 CHECK பண்ணுங்க!
Turnover எவ்வளவு? → Cash Receipts % எவ்வளவு? → Cash Payments % எவ்வளவு? → 44AD/44ADA applicable ஆ? → Section 44AB Tax Audit applicable ஆ?
இந்த 5 checks முடித்த பிறகுதான் சரியான Tax Audit decision எடுக்க வேண்டும்.
“₹1 CRORE TURNOVER தாண்டிட்டதா? 😱 உடனே TAX AUDITன்னு நினைக்காதீங்க!”
Cash Transaction 5%-க்குள் இருந்தால் ₹10 CRORE வரை முக்கிய Tax Audit relaxation இருக்கலாம்! 🔥
ஆனா உங்கள் case-க்கு Section 44AB applicable இருந்தும் 30 September deadline miss பண்ணினால் ₹1.5 LAKH வரை penalty risk! ⚠️
PHOENIX TAX CONSULTANT™
உங்கள் Business-க்கு Tax Audit applicable ஆ இல்லையா?
Turnover மட்டும் பார்த்து முடிவு எடுக்காதீங்க. Cash Transactions + Presumptive Taxation + Books of Accounts + GST/ITR Turnover அனைத்தையும் சரியாக verify பண்ணுங்க.
Phoenix Tax Consultant™ – Your Trusted Tax Partner
📍 Tambaram, Chennai
📞 9940349819 | 8807258797
Income Tax / ITR:
Phoenix Tax – Income Tax & ITR Services
GST:
Phoenix Tax – GST Services
#TaxAudit #TaxAudit2026 #Section44AB #IncomeTax #IncomeTaxIndia #TaxAuditDeadline #ITRFiling #AY202627 #BusinessTax #TaxCompliance #IncomeTaxReturn #GST #GSTR9C #BusinessOwners #TaxConsultant #TaxConsultantChennai #TaxConsultantTambaram #IncomeTaxConsultant #PhoenixTax #Tambaram #Chennai
Quick FAQs
When is tax audit compulsory for AY 2026-27? When business turnover exceeds ₹1 crore, or ₹10 crore if cash receipts and cash payments are each within 5% of the total; for professionals when gross receipts exceed ₹50 lakh (section 44AB).
What was the due date for the tax audit report for AY 2026-27? 21 October 2026, as extended by CBDT Circular No. 07/2026; the ITR for audit cases is due on 21 November 2026.
Which forms are used for tax audit? Form 3CA or 3CB with the statement of particulars in Form 3CD, filed by a chartered accountant on the income tax portal.
What is the penalty for not getting a tax audit done? 0.5% of turnover or gross receipts, up to ₹1.5 lakh, under section 271B, unless there is reasonable cause.
Does a small business under section 44AD need a tax audit? Not if it declares income at the presumptive rate. Audit is needed if it opts out and income exceeds the basic exemption limit.
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration
