 Phoenix Tax Consultant™ November 14, 2026
😮 முன்பணம் வாங்கினீர்களா? Goods-க்கு GST இல்லை… Services-க்கு உடனே GST! | Took an advance? Goods – no GST. Services – GST now!
Took an advance from a customer? Whether GST is due now depends on one thing – are you supplying goods or services?
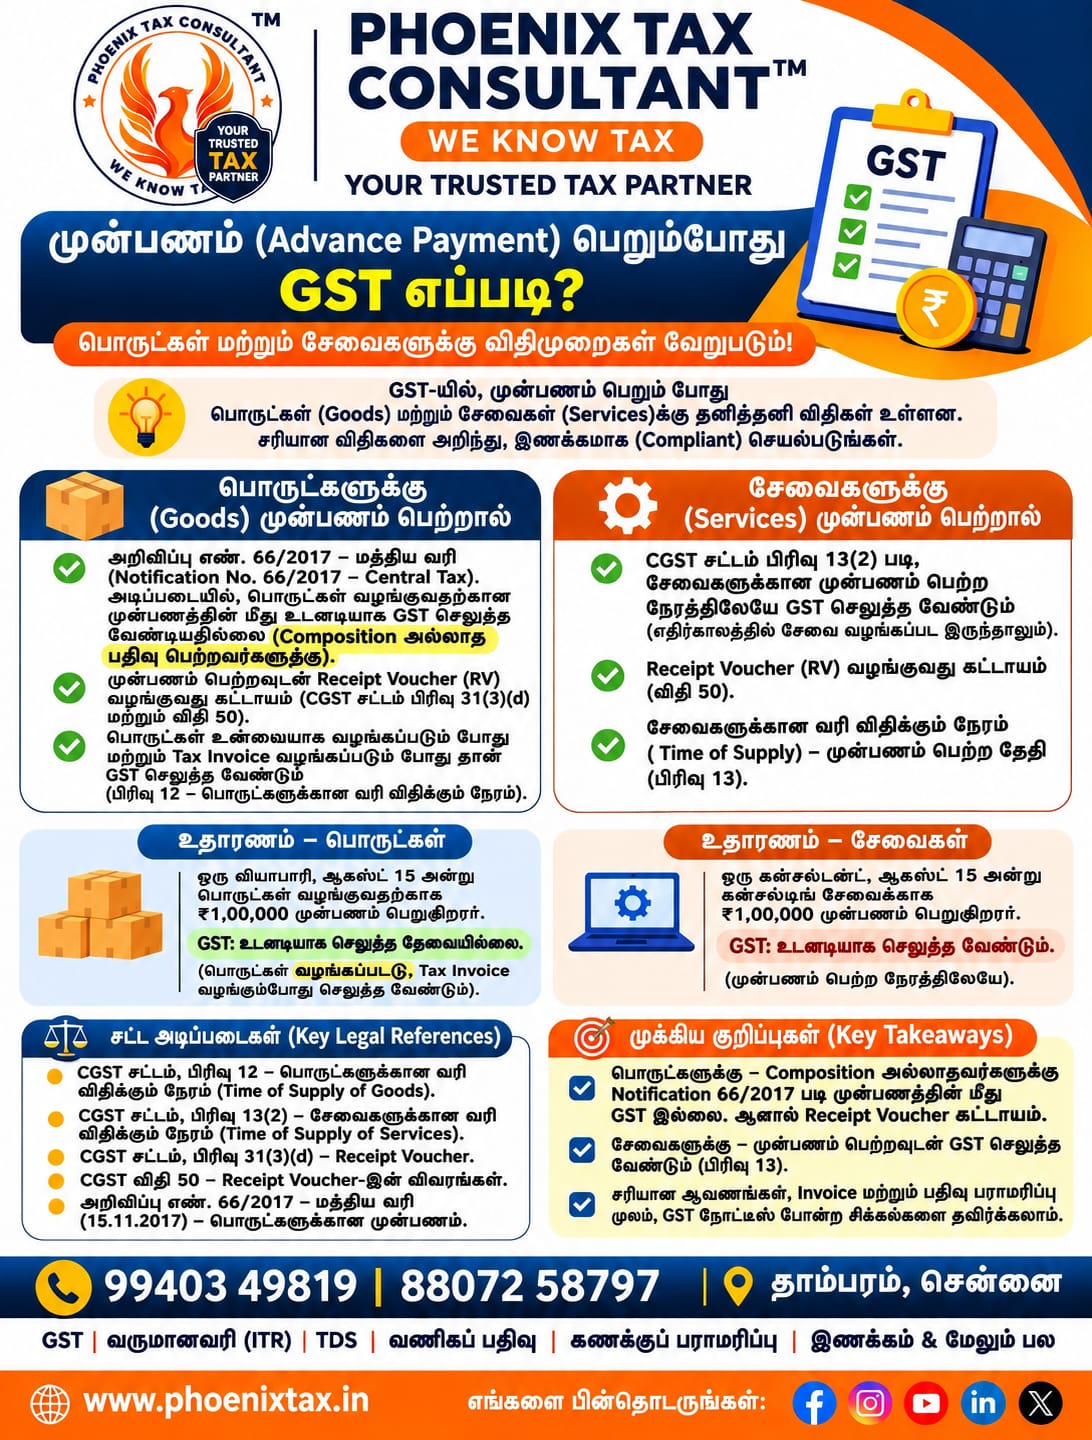
Quick answer: Under CGST, GST on advance received for goods is exempt as per Notification No. 66/2017-Central Tax (15-11-2017). For services, the time of supply is the earlier of invoice date or payment receipt (Section 13(2)), so GST arises when you receive the advance. A Receipt Voucher is required for every advance (Section 31(3)(d), Rule 50).
GST on Advance Payment – Goods
- Notification 66/2017-CT (15-11-2017) exempts tax on advances received for supply of goods (CBIC subject: all taxpayers).
- GST becomes payable when the invoice is issued – Section 12.
- Still issue a Receipt Voucher and keep a separate record of advances.
Example: A trader receives ₹1,00,000 on 15 August for goods to be delivered later → no GST on the advance; GST on the tax invoice.
GST on Advance Payment – Services
- Section 13(2): time of supply = earlier of invoice date (if issued within the prescribed period) or date of receipt of payment.
- So GST is payable in the period you receive the advance, even if the service comes later.
Example: A consultant receives ₹1,00,000 on 15 August for consulting → GST on that advance in the same period, with a Receipt Voucher.
Receipt Voucher – Rule 50
Must show: supplier name, address, GSTIN; serial number; date; recipient details; description of goods/services; advance amount; tax rate and amount; place of supply; reverse-charge status; signature. If the rate is not determinable, Rule 50 proviso says 18%; if the nature of supply is not determinable, it is treated as inter-State. Authority: Section 31(3)(d).
No supply after advance? Section 31(3)(e): issue a Refund Voucher.
Key Takeaways
- Goods advance → no GST on advance; GST at invoice.
- Services advance → GST on receipt.
- Receipt Voucher always.
- Keep clean records to avoid notices.
Related reading: GST 2.0 guide · Add a new place of business in GST · Tax & Compliance Calendar
FAQ
1. Is GST payable on advance received for goods? Exempt under Notification 66/2017-CT dated 15-11-2017; GST is paid when the invoice is issued (Section 12).
2. Is GST payable on advance for services? Yes – Section 13(2).
3. Is a Receipt Voucher mandatory? Yes – Section 31(3)(d); CBIC FAQ confirms every advance.
4. What details go in a Receipt Voucher? Rule 50 lists them.
5. What if the supply never happens? Issue a Refund Voucher – Section 31(3)(e).
6. What if the GST rate isn’t known at advance time? Rule 50 proviso: 18%.
7. What if the nature of supply is unclear? Treated as inter-State (Rule 50 proviso).
8. Do I need a separate account for advances? Yes – CGST Rules require a separate account of advances.
9. Does the goods exemption apply to services? No – goods only.
10. Where can I get GST help in Tambaram, Chennai? Phoenix Tax Consultant™ – 99403 49819 / 88072 58797.
முன்பணம் (Advance Payment) பெறும்போது GST எப்படி? – தாம்பரம், சென்னை
சுருக்கமான பதில்: பொருட்களுக்கான (Goods) முன்பணத்துக்கு GST விலக்கு – Notification No. 66/2017-Central Tax (15-11-2017). சேவைகளுக்கு (Services) Section 13(2) படி, invoice தேதி அல்லது பணம் பெற்ற தேதி – எது முந்தையதோ அதுவே Time of Supply; எனவே முன்பணம் பெறும்போதே GST. எல்லா முன்பணத்துக்கும் Receipt Voucher கட்டாயம் (Section 31(3)(d), Rule 50).
பொருட்கள் (Goods)
- Notification 66/2017-CT படி, முன்பணத்தின் மீது வரி விலக்கு.
- Invoice வழங்கும் போது GST – Section 12.
- Receipt Voucher மற்றும் முன்பணங்களுக்குத் தனிக் கணக்கு அவசியம்.
உதாரணம்: வியாபாரி ஆகஸ்ட் 15-ல் ₹1,00,000 முன்பணம் பெறுகிறார் → முன்பணத்தில் GST இல்லை; Tax Invoice வழங்கும்போது GST.
சேவைகள் (Services)
- Section 13(2): Invoice தேதி அல்லது பணம் பெற்ற தேதி – எது முந்தையதோ.
- சேவை பின்னர் வழங்கப்பட்டாலும், முன்பணம் பெற்ற காலத்திலேயே GST.
உதாரணம்: ஆலோசகர் ஆகஸ்ட் 15-ல் ₹1,00,000 முன்பணம் பெறுகிறார் → அதே காலத்தில் GST + Receipt Voucher.
Receipt Voucher (Rule 50) விவரங்கள்
Supplier பெயர், முகவரி, GSTIN; வரிசை எண்; தேதி; பெறுநர் விவரம்; பொருள்/சேவை விவரம்; முன்பணத் தொகை; வரி விகிதம் & தொகை; Place of Supply; Reverse Charge நிலை; கையொப்பம். வரி விகிதம் தீர்மானிக்க முடியாவிட்டால் 18%; சப்ளையின் தன்மை தெரியாவிட்டால் Inter-State. சப்ளை நடக்கவில்லை என்றால் Refund Voucher – Section 31(3)(e).
முக்கிய குறிப்புகள்
- Goods முன்பணம் → invoice-ல் GST.
- Services முன்பணம் → பெறும்போதே GST.
- Receipt Voucher எப்போதும் தேவை.
- சரியான பதிவுகள் → GST நோட்டீஸ் தவிர்க்கலாம்.
மேலும் படிக்க: GST 2.0 வழிகாட்டி · GST-ல் புதிய வணிக இடம் சேர்ப்பது · Tax & Compliance Calendar
அடிக்கடி கேட்கப்படும் கேள்விகள் (FAQ)
1. Goods முன்பணத்துக்கு GST உண்டா? இல்லை – Notification 66/2017-CT; Invoice-ல் GST.
2. Services முன்பணத்துக்கு GST உண்டா? உண்டு – Section 13(2).
3. Receipt Voucher கட்டாயமா? ஆம் – Section 31(3)(d).
4. Receipt Voucher-ல் என்ன விவரங்கள்? Rule 50-ல் பட்டியலிடப்பட்டுள்ளன.
5. சப்ளை நடக்கவில்லை என்றால்? Refund Voucher – Section 31(3)(e).
6. வரி விகிதம் தெரியாவிட்டால்? 18% (Rule 50 proviso).
7. சப்ளையின் தன்மை தெரியாவிட்டால்? Inter-State ஆகக் கருதப்படும்.
8. முன்பணங்களுக்குத் தனிக் கணக்கு வேண்டுமா? ஆம் – CGST Rules படி.
9. Goods விலக்கு Services-க்கும் பொருந்துமா? இல்லை.
10. தாம்பரம், சென்னையில் GST உதவி எங்கு? Phoenix Tax Consultant™ – 99403 49819 / 88072 58797.
Sources (official): CBIC Central Tax Notifications; CGST Act 2017 Sections 12, 13, 31; CGST Rules 2017 Rule 50. General information; verified 14-11-2026.
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration
