 Phoenix Tax Consultant™ November 10, 2026
Quick Answer: Section 74A of the CGST Act, 2017 is the single provision for GST demand notices and orders for FY 2024-25 onwards. The notice must be issued within 42 months from the annual return due date, and the order within 12 months of the notice (extendable by 6 months). Penalty is 10% of tax or Rs. 10,000 (whichever is higher) in non-fraud cases and 100% of tax in fraud/suppression cases.
சுருக்கமான பதில்: CGST Act Section 74A என்பது FY 2024-25 முதல் GST demand notice மற்றும் order-க்கான ஒரே பிரிவு. Annual return due date-இலிருந்து 42 மாதங்களுக்குள் notice, notice-இலிருந்து 12 மாதங்களுக்குள் order (6 மாதம் நீட்டிக்கலாம்). Fraud இல்லையெனில் penalty வரியின் 10% அல்லது ரூ.10,000 (எது அதிகமோ); fraud / suppression என்றால் வரிக்குச் சமமான 100% penalty.
From FY 2024-25, the old split between Section 73 (non-fraud) and Section 74 (fraud) has been replaced by one section for GST demands. If you run a business in Tambaram, Chennai or anywhere in Tamil Nadu, this change decides how long the department can reopen your returns and how much penalty you pay. Phoenix Tax Consultant™ explains it below in simple English and Tamil, based only on the official CBIC text.
FY 2024-25 முதல், Section 73 (fraud இல்லாத) மற்றும் Section 74 (fraud) என்ற பழைய பிரிவு முறைக்குப் பதிலாக GST demand-க்கு ஒரே பிரிவு வந்துள்ளது. உங்கள் return-களை துறை எத்தனை ஆண்டுகள் வரை மீண்டும் பார்க்கலாம், எவ்வளவு penalty என்பதை இந்த மாற்றமே தீர்மானிக்கிறது. அதிகாரப்பூர்வ CBIC உரையின் அடிப்படையில் Phoenix Tax Consultant™ இதை எளிமையாக விளக்குகிறது.
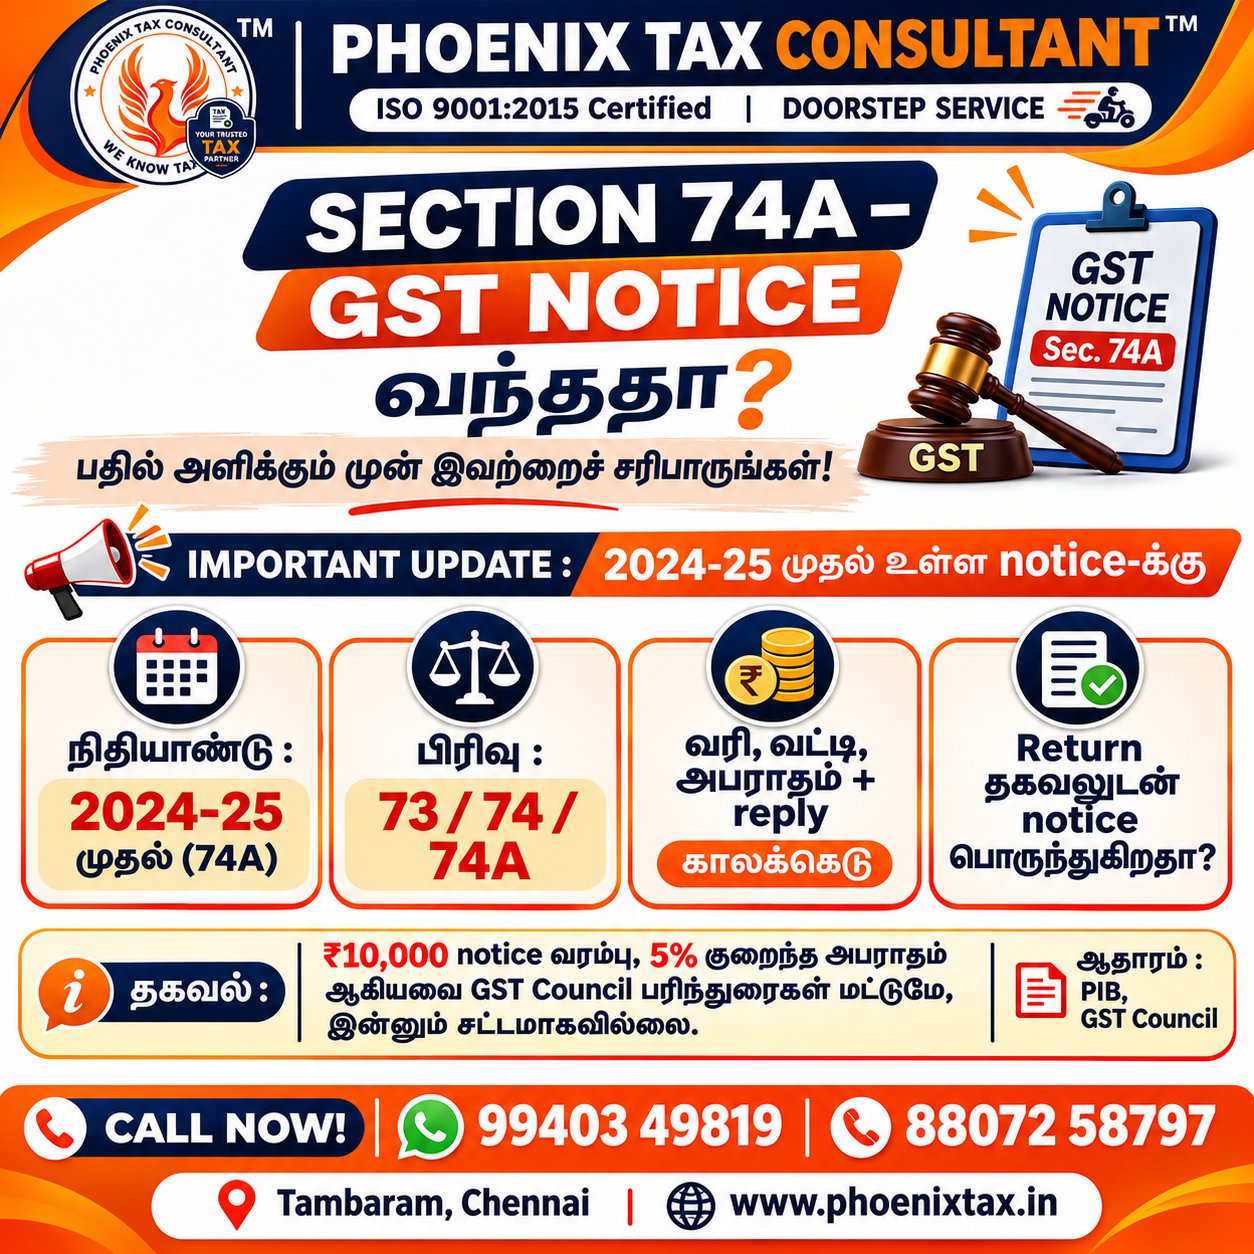
Section 74A at a Glance | Section 74A – முக்கிய விவரங்கள்
| Point / விவரம் | Section 74A (CGST Act) |
|---|---|
| Inserted by / சேர்த்த சட்டம் | Section 138, Finance (No. 2) Act, 2024 (No. 15 of 2024, dated 16.08.2024) |
| In force from / அமல் தேதி | 01.11.2024 – Notification No. 17/2024-Central Tax dated 27.09.2024 |
| Applies to / பொருந்தும் காலம் | Tax pertaining to FY 2024-25 onwards (Section 73 & 74 only up to FY 2023-24) |
| Minimum amount / குறைந்தபட்சம் | No notice if tax / ITC in a FY is below Rs. 1,000 |
| Notice time limit / Notice கால வரம்பு | 42 months from annual return due date (or from erroneous refund date) |
| Order time limit / Order கால வரம்பு | 12 months from notice + max 6 months extension |
| Penalty – non-fraud / fraud இல்லாதது | 10% of tax or Rs. 10,000, whichever is higher |
| Penalty – fraud / suppression | 100% of tax (reduced to 15% / 25% / 50% on early payment) |
Why was Section 74A introduced? | Section 74A ஏன் கொண்டுவரப்பட்டது?
Earlier, Section 73 and Section 74 had different time limits for notices and orders. Section 74A brings one common timeline for both fraud and non-fraud cases for FY 2024-25 onwards. The type of case now changes only the penalty, not the time limit. As per the amended Section 73(12), Sections 73 and 74 continue to apply to the period up to FY 2023-24.
முன்பு Section 73, Section 74 இரண்டிற்கும் notice, order கால வரம்புகள் வேறுவேறாக இருந்தன. FY 2024-25 முதல் fraud, fraud இல்லாத வழக்குகள் இரண்டிற்கும் ஒரே கால வரம்பை Section 74A கொண்டுவருகிறது. வழக்கின் வகை இப்போது penalty-ஐ மட்டுமே மாற்றும். திருத்தப்பட்ட Section 73(12)-இன்படி FY 2023-24 வரையிலான காலத்திற்கு Section 73, 74 தொடர்ந்து பொருந்தும்.
What is the time limit for a Section 74A notice and order? | Notice, Order கால வரம்பு என்ன?
- Notice: within 42 months from the due date of the annual return for the relevant financial year, or 42 months from the date of erroneous refund [Section 74A(2)].
- Order: within 12 months from the date of the notice. If the officer cannot complete it, the Commissioner or an authorised officer (not below Joint Commissioner) may extend it by a maximum of 6 months, recording reasons in writing before the period ends [Section 74A(7)].
- Example: if the annual return due date for a financial year is 31.12.2025, the 42-month notice limit ends on 30.06.2029.
- Notice: அந்த நிதியாண்டின் annual return due date-இலிருந்து 42 மாதங்களுக்குள்; தவறான refund என்றால் refund தேதியிலிருந்து 42 மாதங்கள்.
- Order: notice தேதியிலிருந்து 12 மாதங்களுக்குள். காரணங்களை எழுத்தில் பதிவு செய்து Commissioner அதிகபட்சம் 6 மாதம் நீட்டிக்கலாம்.
- உதாரணம்: annual return due date 31.12.2025 என்றால், notice அனுப்ப கடைசி தேதி 30.06.2029.
How much penalty applies under Section 74A? | எவ்வளவு penalty?
| When you pay / எப்போது செலுத்துகிறீர்கள் | Non-fraud / Fraud இல்லாதது | Fraud / Suppression |
|---|---|---|
| Before notice / Notice-க்கு முன் | Tax + interest, no penalty [74A(8)(i)]* | Tax + interest + 15% penalty [74A(9)(i)] |
| Within 60 days of notice / Notice வந்த 60 நாட்களுக்குள் | Tax + interest, no penalty; proceedings concluded [74A(8)(ii)]* | Tax + interest + 25% penalty; proceedings concluded [74A(9)(ii)] |
| Within 60 days of order / Order வந்த 60 நாட்களுக்குள் | 10% of tax or Rs. 10,000, whichever is higher [74A(5)(i)] | Tax + interest + 50% penalty [74A(9)(iii)] |
| After that / அதன் பிறகு | 10% of tax or Rs. 10,000, whichever is higher | 100% of tax [74A(5)(ii)] |
*Exception – Section 74A(11): if self-assessed tax or tax collected is not paid within 30 days of its due date, the penalty of 10% or Rs. 10,000 (whichever is higher) applies even when you pay early. Interest is payable under Section 50 in every case.
*விதிவிலக்கு – Section 74A(11): self-assessed அல்லது வசூலித்த வரியை due date-இலிருந்து 30 நாட்களுக்குள் செலுத்தாவிட்டால், முன்கூட்டியே செலுத்தினாலும் 10% அல்லது ரூ.10,000 penalty பொருந்தும். எல்லா நிலைகளிலும் Section 50-இன்படி வட்டி உண்டு.
What should you do if you receive a Section 74A notice? | Notice வந்தால் என்ன செய்வது?
- Check the financial year and the notice date against the 42-month limit.
- Reconcile GSTR-1, GSTR-3B, GSTR-2B and books for the period mentioned.
- Check whether the notice alleges fraud / suppression or not – this decides the penalty.
- If the demand is correct, consider paying tax + interest within 60 days of the notice to reduce or avoid penalty.
- If the demand is wrong, file a reply with documents on the GST portal before the due date.
- Notice-இல் உள்ள நிதியாண்டு, notice தேதி 42 மாத வரம்பிற்குள் உள்ளதா எனப் பாருங்கள்.
- அந்தக் காலத்திற்கான GSTR-1, GSTR-3B, GSTR-2B மற்றும் கணக்குப் புத்தகங்களை ஒப்பிடுங்கள்.
- Fraud / suppression குற்றச்சாட்டு உள்ளதா என்று பாருங்கள் – penalty இதைப் பொறுத்தது.
- Demand சரி என்றால், notice வந்த 60 நாட்களுக்குள் வரி + வட்டி செலுத்தி penalty-ஐக் குறைக்கலாம் / தவிர்க்கலாம்.
- Demand தவறு என்றால், ஆவணங்களுடன் GST portal-இல் due date-க்குள் பதில் தாக்கல் செய்யுங்கள்.
Regular and accurate return filing is the best protection. See our GST Return Filing services in Tambaram, Chennai, GST Registration in Chennai and our post on GST notice relief recommended by the 57th GST Council.
சரியான நேரத்தில் துல்லியமான return தாக்கல் செய்வதே சிறந்த பாதுகாப்பு. எங்கள் GST Return Filing சேவை மற்றும் GST Registration சேவை பக்கங்களைப் பாருங்கள்.
Frequently Asked Questions | அடிக்கடி கேட்கப்படும் கேள்விகள்
1. What is Section 74A of the CGST Act?
Section 74A is the single provision for GST demand show cause notices and orders for Financial Year 2024-25 onwards, covering both non-fraud and fraud cases.
CGST Act Section 74A என்றால் என்ன?
FY 2024-25 முதல் GST demand notice மற்றும் order-க்கான ஒரே பிரிவு Section 74A. Fraud இல்லாத மற்றும் fraud வழக்குகள் இரண்டும் இதில் அடங்கும்.
2. From when is Section 74A in force?
It was inserted by section 138 of the Finance (No. 2) Act, 2024 and brought into force from 01.11.2024 by Notification No. 17/2024-Central Tax dated 27.09.2024. It applies to tax pertaining to FY 2024-25 onwards.
Section 74A எப்போது முதல் அமலில் உள்ளது?
Finance (No. 2) Act, 2024 மூலம் சேர்க்கப்பட்டு, Notification No. 17/2024-Central Tax (27.09.2024) மூலம் 01.11.2024 முதல் அமலுக்கு வந்தது. FY 2024-25 மற்றும் அதற்குப் பிந்தைய ஆண்டுகளுக்குப் பொருந்தும்.
3. Do Section 73 and 74 still apply?
Yes, but only for tax pertaining to the period up to FY 2023-24. For FY 2024-25 onwards, Section 74A applies.
Section 73, 74 இன்னும் பொருந்துமா?
ஆம், ஆனால் FY 2023-24 வரையிலான காலத்திற்கு மட்டும். FY 2024-25 முதல் Section 74A பொருந்தும்.
4. What is the time limit for a notice under Section 74A?
42 months from the due date of the annual return for that financial year, or 42 months from the date of erroneous refund.
Section 74A notice-க்கான கால வரம்பு என்ன?
அந்த நிதியாண்டின் annual return due date-இலிருந்து 42 மாதங்கள்; தவறான refund என்றால் refund தேதியிலிருந்து 42 மாதங்கள்.
5. What is the time limit for the order?
12 months from the date of issue of the notice. The Commissioner (or an authorised officer not below Joint Commissioner) can extend it by up to 6 months, with reasons recorded in writing.
Order-க்கான கால வரம்பு என்ன?
Notice தேதியிலிருந்து 12 மாதங்கள். காரணங்களைப் பதிவு செய்து, Commissioner அதிகபட்சம் 6 மாதம் நீட்டிக்கலாம்.
6. Is there a minimum amount for issuing a notice?
Yes. No notice is issued if the tax or wrong ITC in a financial year is less than Rs. 1,000.
Notice அனுப்ப குறைந்தபட்சத் தொகை உண்டா?
ஆம். ஒரு நிதியாண்டில் வரி / தவறான ITC ரூ.1,000-க்கும் குறைவாக இருந்தால் notice அனுப்பப்படாது.
7. What is the penalty in a non-fraud case?
10% of the tax due or Rs. 10,000, whichever is higher. If tax and interest are paid within 60 days of the notice, no penalty is payable (except the case in sub-section 11).
Fraud இல்லாத வழக்கில் penalty எவ்வளவு?
வரியின் 10% அல்லது ரூ.10,000 – இதில் எது அதிகமோ அது. Notice வந்த 60 நாட்களுக்குள் வரி + வட்டி செலுத்தினால் penalty இல்லை (sub-section 11 விதிவிலக்கு தவிர).
8. What is the penalty in a fraud or suppression case?
100% of the tax due. Reduced penalty: 15% if paid before notice, 25% if paid within 60 days of notice, 50% if paid within 60 days of the order (along with tax and interest).
Fraud / suppression வழக்கில் penalty எவ்வளவு?
வரிக்குச் சமமான (100%) penalty. Notice-க்கு முன் செலுத்தினால் 15%, notice வந்த 60 நாட்களுக்குள் 25%, order வந்த 60 நாட்களுக்குள் 50% (வரி + வட்டியுடன்).
9. What if I collected tax but did not pay it within 30 days?
Under sub-section (11), the penalty of 10% or Rs. 10,000 (whichever is higher) applies even if you pay before or within 60 days of the notice, when self-assessed or collected tax is not paid within 30 days of its due date.
வசூலித்த வரியை 30 நாட்களுக்குள் செலுத்தவில்லை என்றால்?
Sub-section (11)-இன்படி, self-assessed / வசூலித்த வரியை due date-இலிருந்து 30 நாட்களுக்குள் செலுத்தாவிட்டால், முன்கூட்டியே செலுத்தினாலும் 10% அல்லது ரூ.10,000 penalty பொருந்தும்.
10. What does suppression mean under GST?
Explanation 2 to Section 74A defines suppression as not declaring facts that must be declared in a return, statement or document, or not furnishing information asked for in writing by the proper officer.
GST-இல் suppression என்றால் என்ன?
Return / statement / ஆவணத்தில் அறிவிக்க வேண்டிய விவரங்களை அறிவிக்காதது, அல்லது அதிகாரி எழுத்து மூலம் கேட்ட தகவலைத் தராதது – இதுவே suppression (Explanation 2).
Official sources: CGST Act Section 74A – CBIC | CGST Act Section 73 – CBIC | cbic-gst.gov.in | gst.gov.in. Information as on 10.11.2026. This article is for general awareness and is not legal advice.
Got a GST Notice? | GST Notice வந்ததா?
Phoenix Tax Consultant™ (ISO 9001:2015 Certified) helps businesses in Tambaram, Chennai and across Tamil Nadu with GST notice replies, reconciliation and return filing.
Call: 99403 49819 | 88072 58797 | Email: jai@phoenixtax.in
No. 10A, 2nd Floor, Rajendra Building, Duraisamy Pillai Street, West Tambaram, Chennai – 600045
Related services: GST Return Filing | GST Registration | Income Tax Return Filing
Official reference: CBIC – Section 74A | GST Portal
