 Phoenix Tax Consultant™ November 16, 2026
Next advance tax instalment: 15 December (75% cumulative). Do you need to pay it? Check before interest starts.
அடுத்த advance tax தவணை 15 December (மொத்தம் 75%). நீங்கள் செலுத்த வேண்டுமா? வட்டி வருவதற்கு முன் சரிபாருங்கள்.
Quick Answer: Advance tax is payable if your net tax for the year is Rs 10,000 or more after TDS/TCS and credits. Instalments: 15% by 15 June, 45% by 15 September, 75% by 15 December, 100% by 15 March (Section 408).
Near me: Need help to pay advance tax near me? Phoenix Tax Consultant™, Tambaram, Chennai – 99403 49819 / 88072 58797.
விரைவு பதில்: TDS/TCS, credit கழித்த பின் நிகர வரி ₹10,000 அல்லது அதற்கு மேல் என்றால் advance tax கட்டாயம். 15 June – 15%, 15 September – 45%, 15 December – 75%, 15 March – 100% (பிரிவு 408).
அருகில் உதவி: Advance tax செலுத்த உதவி near me தேடுகிறீர்களா? தாம்பரம், சென்னை – Phoenix Tax Consultant™: 99403 49819 / 88072 58797.
Who Must Pay Advance Tax?
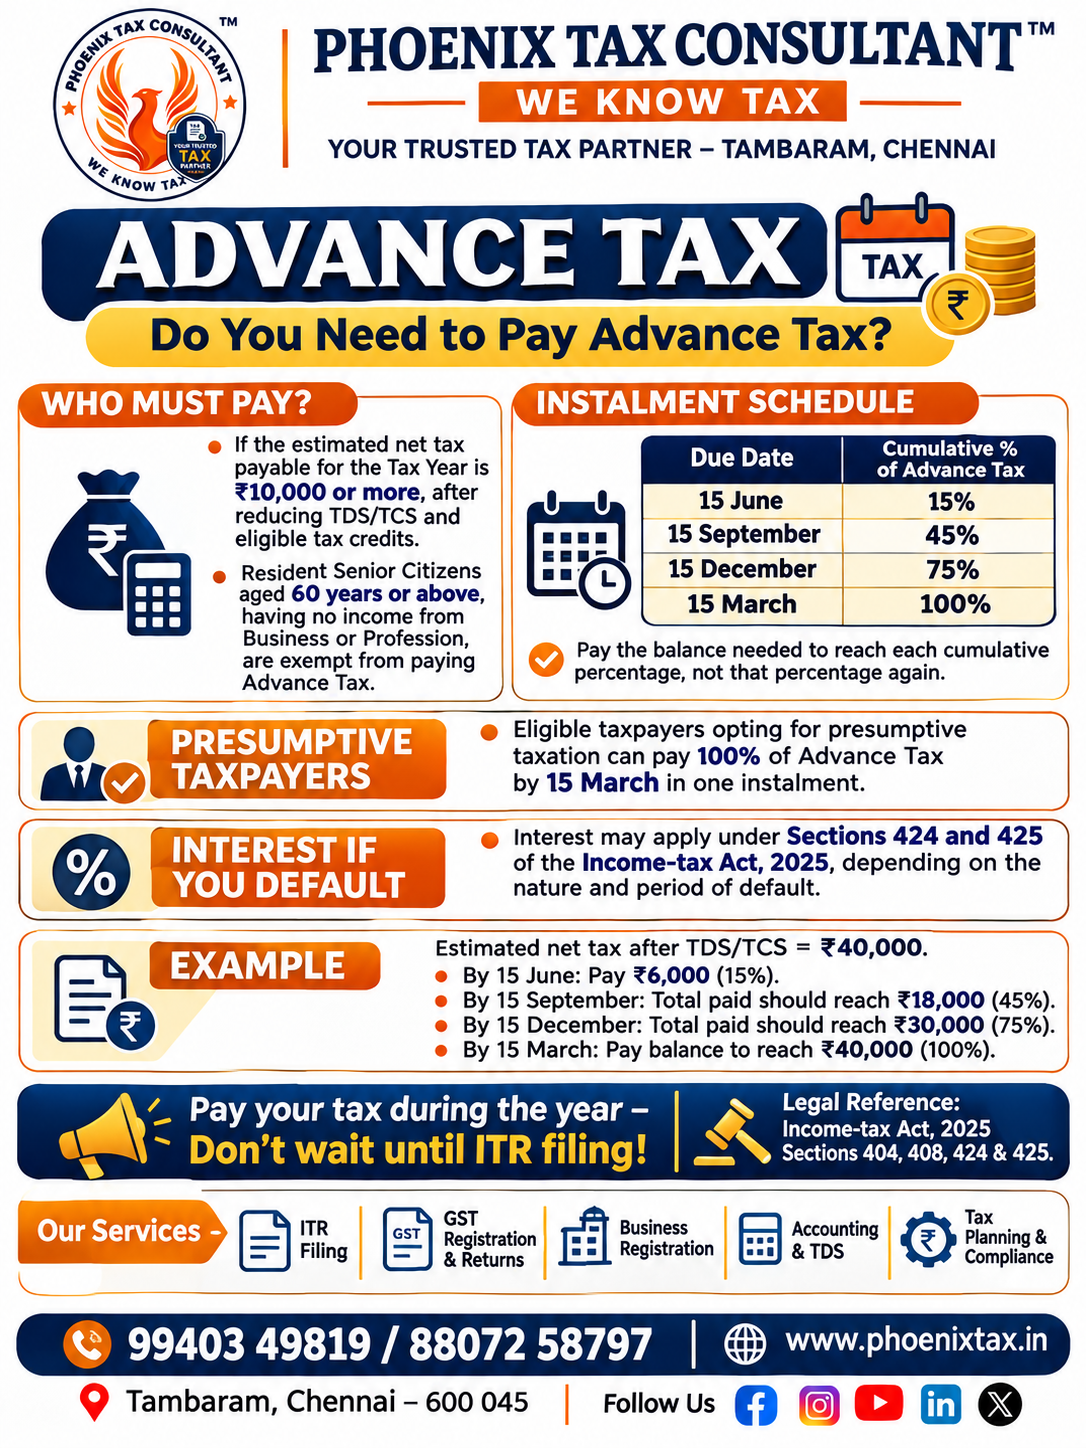
Under Section 404 of the Income-tax Act, 2025, advance tax is payable when the tax payable for the year is Rs 10,000 or more. A resident senior citizen (60 years or above) with no business or professional income is not liable (official FAQ). Individuals with only salary income are generally covered by employer TDS.
Advance Tax யார் செலுத்த வேண்டும்?
Income-tax Act, 2025 பிரிவு 404-ன்படி ஆண்டுக்கான வரி ₹10,000 அல்லது அதற்கு மேல் இருந்தால் advance tax கட்டாயம். Business / profession வருமானம் இல்லாத, இந்தியாவில் வசிக்கும் 60 வயது அல்லது மேற்பட்ட மூத்த குடிமக்களுக்கு விலக்கு உண்டு (அதிகாரப்பூர்வ FAQ). சம்பளம் மட்டும் உள்ளவர்களுக்கு employer TDS பிடிப்பார். தொடர்புடைய கட்டுரை: Income Tax Return filing in Tambaram, Chennai.
Instalment Schedule (Section 408)
| Due Date / தேதி | Cumulative % / மொத்த % |
|---|---|
| 15 June | 15% |
| 15 September | 45% |
| 15 December | 75% |
| 15 March | 100% |
Pay only the balance needed to reach each cumulative percentage. Tax paid on or before 31 March is treated as advance tax for that year (Section 408). See also our tax compliance calendar.
தவணை அட்டவணை (பிரிவு 408)
ஒவ்வொரு cumulative சதவீதத்தையும் எட்டத் தேவையான மீதித் தொகையை மட்டும் செலுத்துங்கள். 31 March-க்குள் செலுத்தப்படும் வரி அந்த ஆண்டின் advance tax ஆகக் கருதப்படும் (பிரிவு 408). பார்க்க: வரி compliance காலண்டர்.
Presumptive Taxpayers
Taxpayers covered by Section 58(2) (Table Sl. No. 1 or 3) can pay 100% of advance tax in one instalment on or before 15 March (Section 408(2)). Those under Table Sl. No. 2 must follow the regular instalments (incometax.gov.in FAQ).
Presumptive வரி செலுத்துவோர்
பிரிவு 58(2) (Table Sl. No. 1 அல்லது 3) கீழ் வருபவர்கள் 100% advance tax-ஐ 15 March-க்குள் ஒரே தவணையாகச் செலுத்தலாம் (பிரிவு 408(2)). Table Sl. No. 2 கீழ் வருபவர்கள் வழக்கமான தவணைகளைப் பின்பற்ற வேண்டும்.
Example: Net Tax Rs 40,000
| Date | Total to be paid |
|---|---|
| 15 June (15%) | Rs 6,000 |
| 15 September (45%) | Rs 18,000 |
| 15 December (75%) | Rs 30,000 |
| 15 March (100%) | Rs 40,000 |
உதாரணம்: நிகர வரி ₹40,000
15 June-க்குள் ₹6,000; 15 September-க்குள் மொத்தம் ₹18,000; 15 December-க்குள் மொத்தம் ₹30,000; 15 March-க்குள் மொத்தம் ₹40,000 (இது உதாரணம் மட்டுமே).
Interest If You Default (Sections 424 and 425)
Under Section 424, simple interest at 1% per month or part of a month applies if advance tax is not paid or is below 90% of the assessed tax. Section 425 applies for deferment of instalments when payment is below 12% (15 June), 36% (15 September), 75% (15 December) or 100% (15 March) (official interest FAQ).
வட்டி (பிரிவு 424, 425)
பிரிவு 424-ன்படி advance tax செலுத்தாவிட்டால் அல்லது assessed tax-ல் 90%-க்கும் குறைவாக இருந்தால் மாதம் அல்லது மாதப் பகுதிக்கு 1% simple interest. தவணை தாமதத்துக்கு பிரிவு 425: 15 June-க்குள் 12%, 15 September-க்குள் 36%, 15 December-க்குள் 75%, 15 March-க்குள் 100%-க்கும் குறைவாக இருந்தால் (அதிகாரப்பூர்வ வட்டி FAQ).
Advance Tax Help Near Me – Tambaram, Chennai
Phoenix Tax Consultant™ helps freelancers, business owners, professionals and investors in Tambaram, Chromepet, Pallavaram, Selaiyur, Perungalathur and across Chennai to estimate and pay advance tax on time. Also read income tax consultant near me, Tambaram. Call 99403 49819 / 88072 58797.
Advance Tax உதவி near me – தாம்பரம், சென்னை
தாம்பரம், குரோம்பேட்டை, பல்லாவரம், சேலையூர், பெருங்களத்தூர் மற்றும் சென்னை முழுவதும் freelancer, வணிகர், professional, முதலீட்டாளர்களுக்கு advance tax கணக்கிட்டு சரியான நேரத்தில் செலுத்த Phoenix Tax Consultant™ உதவுகிறது. பார்க்க: Form 26AS, AIS, TIS. 99403 49819 / 88072 58797.
FAQs / அடிக்கடி கேட்கப்படும் கேள்விகள்
1. Who must pay advance tax?
Anyone whose tax payable for the year is Rs 10,000 or more after TDS/TCS and eligible tax credits (Section 404, Income-tax Act, 2025).
Advance tax யார் செலுத்த வேண்டும்?
TDS/TCS, தகுதியான tax credit கழித்த பின் வரி ₹10,000 அல்லது அதற்கு மேல் இருந்தால் (Income-tax Act, 2025 – பிரிவு 404).
2. What are the advance tax due dates and percentages?
15 June: 15%, 15 September: 45%, 15 December: 75%, 15 March: 100% (cumulative), as per Section 408(1).
Advance tax due date, சதவீதம் என்ன?
15 June – 15%, 15 September – 45%, 15 December – 75%, 15 March – 100% (cumulative); பிரிவு 408(1).
3. Are senior citizens exempt from advance tax?
A resident senior citizen (60 years or above) with no income from business or profession is not liable to pay advance tax.
மூத்த குடிமக்களுக்கு advance tax விலக்கு உண்டா?
Business அல்லது profession வருமானம் இல்லாத, இந்தியாவில் வசிக்கும் 60 வயது அல்லது மேற்பட்டவர்கள் advance tax செலுத்த வேண்டியதில்லை.
4. Do salaried employees need to pay advance tax?
Individuals with only salary income are generally not required, as the employer deducts TDS. If you have other income and net tax is Rs 10,000 or more, advance tax applies.
சம்பளம் பெறுபவர்கள் advance tax செலுத்த வேண்டுமா?
சம்பளம் மட்டுமே உள்ளவர்களுக்கு employer TDS பிடிப்பதால் பொதுவாகத் தேவையில்லை. வேறு வருமானம் இருந்து, நிகர வரி ₹10,000 அல்லது அதற்கு மேல் என்றால் செலுத்த வேண்டும்.
5. What is the rule for presumptive taxation taxpayers?
Taxpayers under Section 58(2) (Table Sl. No. 1 or 3) can pay the whole advance tax in one instalment on or before 15 March (Section 408(2)).
Presumptive taxation செய்பவர்களுக்கு விதி என்ன?
பிரிவு 58(2) (Table Sl. No. 1 அல்லது 3) கீழ் வருபவர்கள் முழு advance tax-ஐயும் 15 March-க்குள் ஒரே தவணையாகச் செலுத்தலாம் (பிரிவு 408(2)).
6. How do I calculate each instalment?
Pay only the balance needed to reach the cumulative percentage. Example: net tax Rs 40,000 gives Rs 6,000 by 15 June, total Rs 18,000 by 15 September, Rs 30,000 by 15 December and Rs 40,000 by 15 March.
ஒவ்வொரு தவணையையும் எப்படிக் கணக்கிடுவது?
Cumulative சதவீதத்தை எட்ட தேவையான மீதியை மட்டும் செலுத்துங்கள். உதாரணம்: நிகர வரி ₹40,000 எனில் 15 June-க்குள் ₹6,000, 15 September-க்குள் மொத்தம் ₹18,000, 15 December-க்குள் ₹30,000, 15 March-க்குள் ₹40,000.
7. What interest applies if I do not pay advance tax?
Section 424 provides simple interest at 1% per month or part of a month if advance tax is not paid or is less than 90% of the assessed tax. Section 425 covers deferment of instalments.
Advance tax செலுத்தாவிட்டால் என்ன வட்டி?
பிரிவு 424-ன்படி advance tax செலுத்தாவிட்டால் அல்லது assessed tax-ல் 90%-க்கும் குறைவாக இருந்தால் மாதத்திற்கு 1% simple interest. தவணை தாமதத்துக்கு பிரிவு 425 பொருந்தும்.
8. When does interest under Section 425 apply?
If tax paid by 15 June is below 12%, by 15 September below 36%, by 15 December below 75% or by 15 March below 100% of the assessed tax.
பிரிவு 425 வட்டி எப்போது பொருந்தும்?
15 June-க்குள் 12%-க்கும், 15 September-க்குள் 36%-க்கும், 15 December-க்குள் 75%-க்கும், 15 March-க்குள் 100%-க்கும் குறைவாகச் செலுத்தினால்.
9. What if the due date is a bank holiday?
The official FAQ states that payment on the next working day does not attract interest.
Due date வங்கி விடுமுறை என்றால்?
அடுத்த வேலை நாளில் செலுத்தினால் வட்டி இல்லை என்று அதிகாரப்பூர்வ FAQ கூறுகிறது.
10. Is tax paid after 15 March but by 31 March treated as advance tax?
Yes. Any amount paid by advance tax on or before 31 March is treated as advance tax paid for that financial year (Section 408(3)), but interest for the earlier shortfall can still apply.
15 March-க்குப் பிறகு 31 March-க்குள் செலுத்தினால் advance tax ஆகுமா?
ஆம். 31 March-க்குள் செலுத்தப்படும் advance tax அந்த நிதியாண்டின் advance tax ஆகக் கருதப்படும் (பிரிவு 408(3)); ஆனால் முந்தைய தவணை குறைவுக்கு வட்டி பொருந்தலாம்.
Official Sources
- Income-tax Act, 2025 – Section 404
- Income-tax Act, 2025 – Section 408
- Income-tax Act, 2025 – Section 424
- Income Tax Dept – FAQs on interest under sections 423–426
- Income Tax Dept – FAQs on Advance Tax
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration
