 Phoenix Tax Consultant™ November 16, 2026
Paying 18% GST when 1% could be enough? Many small shops never check whether the composition scheme fits them. Here is the difference, checked against the Act and Rules.
1% போதுமான இடத்தில் 18% GST கட்டுகிறீர்களா? Composition scheme தங்களுக்குப் பொருந்துமா என்று பல சிறு கடைகள் பார்ப்பதே இல்லை. Act மற்றும் Rules-உடன் சரிபார்த்த வேறுபாடுகள் இதோ.
Quick Answer | சுருக்கமான பதில்
The composition scheme under GST lets small businesses pay 1%, 5% or 6% of turnover, with a limit of ₹1.5 crore for goods and ₹50 lakh for services. You cannot claim ITC, collect GST or sell to other States. Regular GST has no turnover limit and allows ITC. Looking for a GST consultant near me? Phoenix Tax Consultant™ serves Tambaram, Chennai.
GST composition scheme-ல் சிறு வணிகங்கள் turnover-ல் 1%, 5% அல்லது 6% வரி செலுத்தலாம்; வரம்பு பொருட்களுக்கு ₹1.5 கோடி, சேவைகளுக்கு ₹50 லட்சம். ITC எடுக்கவோ, GST வசூலிக்கவோ, வெளி மாநிலத்துக்கு விற்கவோ முடியாது. Regular GST-ல் turnover வரம்பு இல்லை, ITC உண்டு. GST consultant near me தேடுகிறீர்களா? Tambaram, Chennai-ல் Phoenix Tax Consultant™ உதவும்.
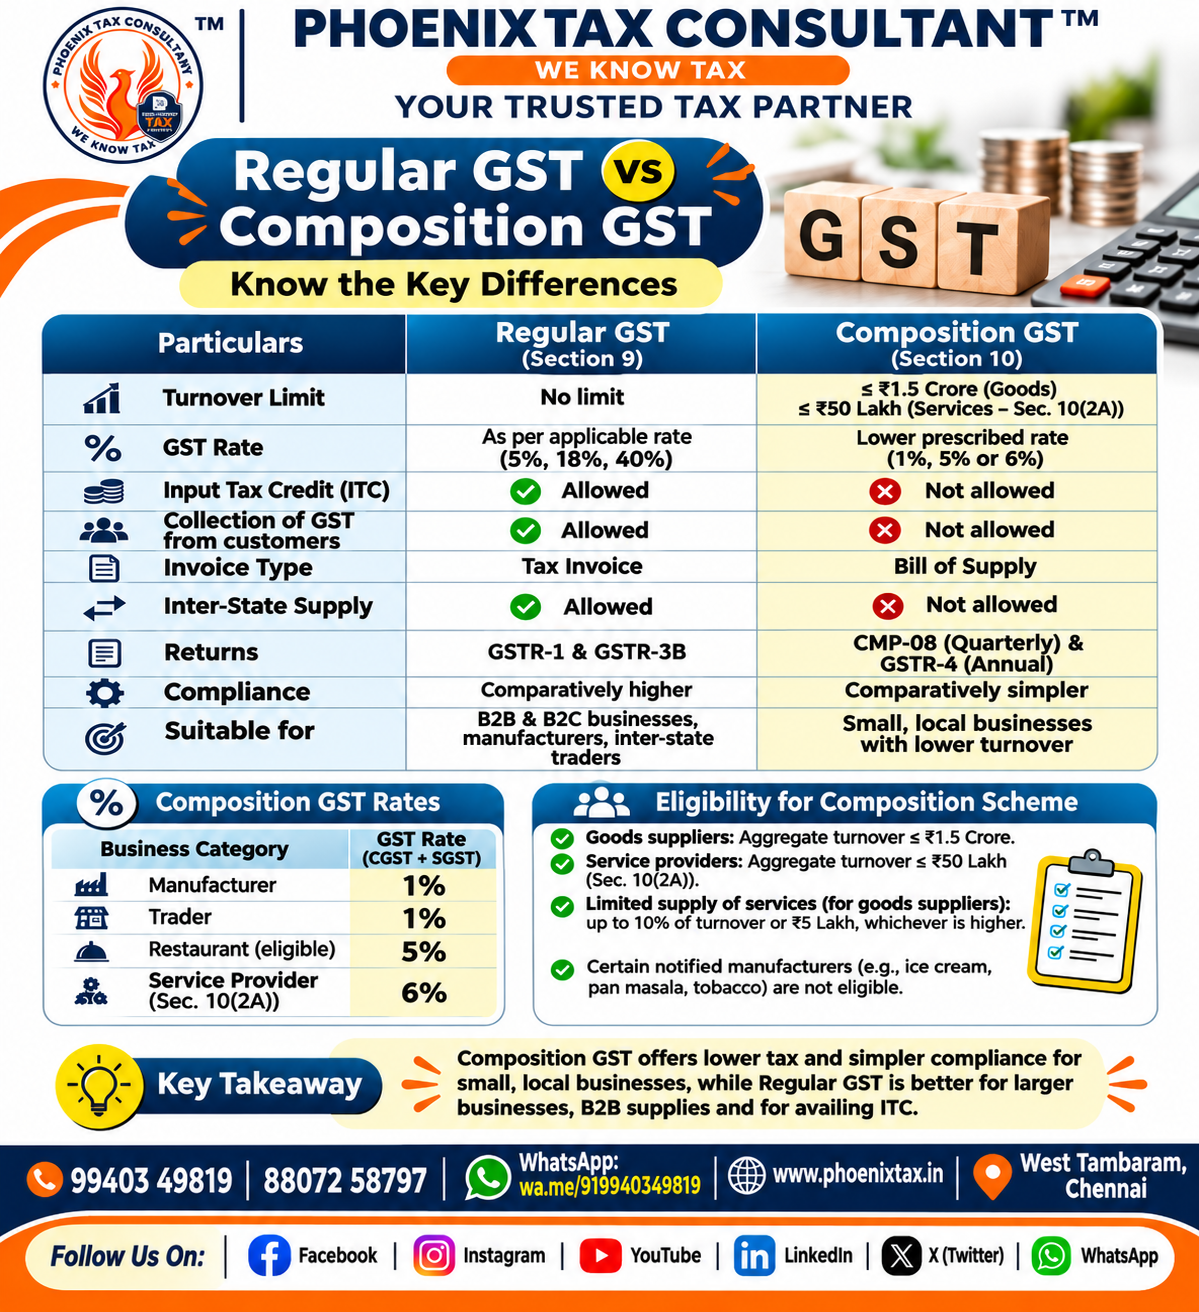
Regular GST vs composition scheme under GST: key differences
| Particulars | Regular GST (Section 9) | Composition scheme (Section 10) |
|---|---|---|
| Turnover limit | No limit | ₹1.5 crore (goods, restaurants); ₹50 lakh (services, Section 10(2A)) |
| Tax rate | Applicable rate: 5%, 18% or 40% | 1%, 5% or 6% of turnover |
| Input tax credit | Allowed | Not allowed |
| Collecting GST from customers | Allowed | Not allowed |
| Document issued | Tax invoice | Bill of supply |
| Sales to other States | Allowed | Not allowed |
| Returns | GSTR-1 and GSTR-3B | CMP-08 (quarterly) and GSTR-4 (annual) |
Regular rates changed from 22 September 2025: the 56th GST Council moved GST to two main rates, 5% and 18%, with a special 40% rate. The old 12% and 28% slabs no longer apply. See our GST 2.0 rate guide.
Regular GST vs composition scheme: முக்கிய வேறுபாடுகள்
Regular GST-ல் (Section 9) turnover வரம்பு இல்லை; 5%, 18% அல்லது 40% என்ற விகிதத்தில் வரி, ITC உண்டு, வாடிக்கையாளரிடம் GST வசூலிக்கலாம், tax invoice வழங்கலாம், வெளி மாநிலங்களுக்கு விற்கலாம்; GSTR-1 மற்றும் GSTR-3B தாக்கல் செய்ய வேண்டும். Composition scheme-ல் (Section 10) வரம்பு ₹1.5 கோடி (பொருட்கள், restaurants) அல்லது ₹50 லட்சம் (சேவைகள்); turnover-ல் 1%, 5% அல்லது 6% வரி; ITC இல்லை, GST வசூலிக்க முடியாது, bill of supply மட்டும், வெளி மாநில விற்பனை இல்லை; CMP-08 (காலாண்டு) மற்றும் GSTR-4 (ஆண்டு) தாக்கல்.
22 செப்டம்பர் 2025 முதல் regular விகிதங்கள் மாறியுள்ளன: 56-வது GST Council, 5% மற்றும் 18% என்ற இரண்டு முக்கிய விகிதங்களையும், 40% சிறப்பு விகிதத்தையும் கொண்டு வந்தது. பழைய 12%, 28% slabs இப்போது இல்லை. எங்கள் GST 2.0 rate guide பார்க்கவும்.
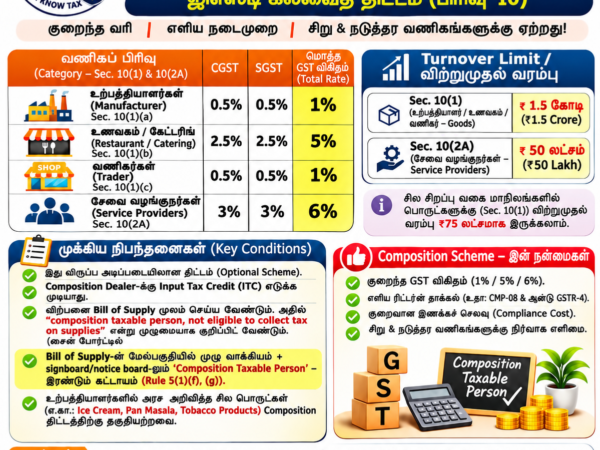
GST composition scheme limit and rates
| Business category | Rate (CGST + SGST) | Turnover limit |
|---|---|---|
| Manufacturer | 1% of turnover | ₹1.5 crore |
| Trader | 1% of taxable turnover | ₹1.5 crore |
| Restaurant | 5% of turnover | ₹1.5 crore |
| Service provider (Section 10(2A)) | 6% of turnover | ₹50 lakh |
The limit is tested on aggregate turnover of the preceding financial year. In eight States (Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura and Uttarakhand) it is ₹75 lakh. The option lapses on the day your turnover crosses the limit during the year.
GST composition scheme வரம்பு மற்றும் விகிதங்கள்
உற்பத்தியாளர்: turnover-ல் 1%; வணிகர்: taxable turnover-ல் 1%; restaurant: 5%; இவை மூன்றுக்கும் வரம்பு ₹1.5 கோடி. Section 10(2A) சேவை வழங்குநர்: 6%, வரம்பு ₹50 லட்சம். வரம்பு, முந்தைய நிதியாண்டின் aggregate turnover-ஐ வைத்துப் பார்க்கப்படும். எட்டு மாநிலங்களில் (Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, Uttarakhand) வரம்பு ₹75 லட்சம். ஆண்டின் நடுவில் turnover வரம்பைத் தாண்டும் நாளிலேயே இந்த விருப்பம் முடிந்துவிடும்.
Who can opt and who cannot
- Goods suppliers and restaurants within ₹1.5 crore; service providers within ₹50 lakh.
- Goods suppliers may also supply services up to 10% of last year’s State turnover or ₹5 lakh, whichever is higher.
- Not allowed: inter-State outward supplies.
- Not eligible: manufacturers of ice cream, pan masala, tobacco products and aerated water; casual and non-resident taxable persons.
- All registrations under one PAN must opt together.
New to GST? Start with GST registration in Tambaram, Chennai.
யார் தேர்வு செய்யலாம், யார் முடியாது
- ₹1.5 கோடிக்குள் உள்ள பொருள் விற்பனையாளர்கள், restaurants; ₹50 லட்சத்துக்குள் உள்ள சேவை வழங்குநர்கள்.
- பொருள் விற்பனையாளர்கள், முந்தைய ஆண்டு மாநில turnover-ல் 10% அல்லது ₹5 லட்சம் (எது அதிகமோ) வரை சேவைகளும் வழங்கலாம்.
- அனுமதி இல்லை: வெளி மாநிலங்களுக்கு விற்பனை.
- தகுதி இல்லை: ice cream, pan masala, tobacco பொருட்கள், aerated water உற்பத்தியாளர்கள்; casual மற்றும் non-resident taxable persons.
- ஒரே PAN-ல் உள்ள அனைத்து registrations-ம் சேர்ந்தே தேர்வு செய்ய வேண்டும்.
GST-க்கு புதியவரா? Tambaram, Chennai GST registration பக்கத்திலிருந்து தொடங்குங்கள்.
Returns and due dates
Composition taxpayers file FORM GST CMP-08 by the 18th of the month after each quarter and FORM GSTR-4 by 30 June after the financial year (FY 2024-25 onwards). Regular taxpayers file GSTR-1 and GSTR-3B; see our GST return filing services and why NIL returns are still mandatory.
Returns மற்றும் கடைசி தேதிகள்
Composition வரி செலுத்துவோர், ஒவ்வொரு காலாண்டும் முடிந்த அடுத்த மாதம் 18-ம் தேதிக்குள் FORM GST CMP-08-ஐயும், நிதியாண்டு முடிந்த பிறகு வரும் ஜூன் 30-க்குள் FORM GSTR-4-ஐயும் (FY 2024-25 முதல்) தாக்கல் செய்ய வேண்டும். Regular வரி செலுத்துவோர் GSTR-1, GSTR-3B தாக்கல் செய்ய வேண்டும்; எங்கள் GST return filing சேவைகள் மற்றும் NIL return ஏன் கட்டாயம் பதிவுகளைப் பார்க்கவும்.
What is new: portal change from 1 November 2026
A GST portal advisory dated 1 November 2026 adds a separate composition category, “Person eligible for composition levy under Section 10(2A)”. It applies to applications in FORM REG-01, CMP-02, CMP-04 and REG-14. Service providers opting in should pick this category.
புதியது: 1 நவம்பர் 2026 முதல் portal மாற்றம்
1 நவம்பர் 2026 தேதியிட்ட GST portal advisory, “Person eligible for composition levy under Section 10(2A)” என்ற தனி composition category-ஐச் சேர்த்துள்ளது. FORM REG-01, CMP-02, CMP-04, REG-14 விண்ணப்பங்களுக்கு இது பொருந்தும். Composition தேர்வு செய்யும் சேவை வழங்குநர்கள் இந்த category-ஐத் தேர்ந்தெடுக்க வேண்டும்.
Which one suits your business?
Composition suits small local shops and restaurants that sell mostly to consumers and want simple compliance. Regular GST suits businesses that sell to other registered businesses, sell outside the State or need ITC, because buyers cannot take credit on a bill of supply.
உங்கள் வணிகத்துக்கு எது பொருந்தும்?
பெரும்பாலும் நுகர்வோருக்கு விற்கும், எளிய compliance விரும்பும் சிறு உள்ளூர் கடைகள் மற்றும் restaurants-க்கு composition பொருந்தும். மற்ற registered வணிகங்களுக்கு விற்பவர்கள், வெளி மாநிலங்களுக்கு விற்பவர்கள், ITC தேவைப்படுபவர்களுக்கு regular GST பொருந்தும்; ஏனெனில் bill of supply-ஐ வைத்து வாங்குபவர் credit எடுக்க முடியாது.
Composition scheme help near me – Tambaram, Chennai
Phoenix Tax Consultant™ helps businesses in Tambaram, Chromepet, Pallavaram, Selaiyur, Perungalathur and across Chennai choose the right GST scheme and file on time. We offer online service across Tamil Nadu and doorstep service in Chennai and nearby areas. Learn more about our GST consultant in Tambaram services.
Composition scheme உதவி near me – Tambaram, Chennai
Tambaram, Chromepet, Pallavaram, Selaiyur, Perungalathur மற்றும் சென்னை முழுவதும் உள்ள வணிகங்களுக்கு, சரியான GST திட்டத்தைத் தேர்ந்தெடுக்கவும் நேரத்தில் தாக்கல் செய்யவும் Phoenix Tax Consultant™ உதவுகிறது. தமிழ்நாடு முழுவதும் online சேவையும், சென்னை மற்றும் சுற்றுப்புறங்களில் doorstep சேவையும் உண்டு.
Frequently Asked Questions | அடிக்கடி கேட்கப்படும் கேள்விகள்
1. What is the composition scheme under GST?
It is an optional scheme under Section 10 of the CGST Act for small taxpayers. You pay tax at a fixed percentage of turnover instead of the normal GST rate, and you file a quarterly statement and one annual return.
இது CGST Act Section 10-ன் கீழ் சிறு வரி செலுத்துவோருக்கான விருப்பத் திட்டம். வழக்கமான GST விகிதத்திற்குப் பதிலாக turnover-ல் ஒரு நிலையான சதவீதத்தை வரியாகச் செலுத்தலாம்; காலாண்டுக்கு ஒரு statement, ஆண்டுக்கு ஒரு return தாக்கல் செய்தால் போதும்.
2. What is the GST composition scheme limit?
Aggregate turnover in the preceding financial year must not exceed ₹1.5 crore for goods suppliers and restaurants (Notification 14/2019-Central Tax). For service providers under Section 10(2A) the limit is ₹50 lakh. Eight States, such as Uttarakhand and Sikkim, have a ₹75 lakh limit; Tamil Nadu is not one of them.
முந்தைய நிதியாண்டின் aggregate turnover, பொருள் விற்பனையாளர்கள் மற்றும் restaurants-க்கு ₹1.5 கோடியைத் தாண்டக் கூடாது (Notification 14/2019-Central Tax). Section 10(2A)-ன் கீழ் சேவை வழங்குநர்களுக்கு வரம்பு ₹50 லட்சம். Uttarakhand, Sikkim போன்ற எட்டு மாநிலங்களில் வரம்பு ₹75 லட்சம்; தமிழ்நாடு அதில் இல்லை.
3. What are the composition scheme rates?
Rule 7 of the CGST Rules prescribes the central tax, and an equal State tax applies: manufacturers 1%, traders 1% of taxable turnover, restaurants 5%, and service providers under Section 10(2A) 6%.
CGST Rules-ன் Rule 7 central tax-ஐ நிர்ணயிக்கிறது; அதற்குச் சமமான State tax-ம் சேரும்: உற்பத்தியாளர்கள் 1%, வணிகர்கள் taxable turnover-ல் 1%, restaurants 5%, Section 10(2A) சேவை வழங்குநர்கள் 6%.
4. Can a composition dealer claim input tax credit?
No. Section 10(4) says a composition taxpayer cannot take input tax credit and cannot collect tax from customers.
முடியாது. Section 10(4)-ன்படி composition வரி செலுத்துபவர் input tax credit எடுக்கவும் முடியாது, வாடிக்கையாளரிடம் வரி வசூலிக்கவும் முடியாது.
5. Can a composition dealer issue a tax invoice?
No. A person paying tax under Section 10 issues a bill of supply instead of a tax invoice, under Section 31(3)(c). CBIC's FAQ says the words 'composition taxable person, not eligible to collect tax on supplies' go at the top of the bill.
முடியாது. Section 10-ன் கீழ் வரி செலுத்துபவர், Section 31(3)(c)-ன்படி tax invoice-க்குப் பதிலாக bill of supply வழங்க வேண்டும். Bill-ன் மேல் 'composition taxable person, not eligible to collect tax on supplies' என்று குறிப்பிட வேண்டும் என CBIC FAQ கூறுகிறது.
6. Can a composition dealer sell to other States?
No. Inter-State outward supplies are not allowed under Section 10. Buying from other States is not restricted, as CBIC's composition FAQ notes.
முடியாது. Section 10-ன் கீழ் வெளி மாநிலங்களுக்கு விற்பனை (inter-State outward supply) அனுமதி இல்லை. வெளி மாநிலத்திலிருந்து கொள்முதல் செய்வதற்குத் தடை இல்லை என CBIC composition FAQ குறிப்பிடுகிறது.
7. Which returns does a composition taxpayer file?
FORM GST CMP-08 every quarter, by the 18th of the month after the quarter, and FORM GSTR-4 once a year, by 30 June after the financial year (from FY 2024-25 onwards), under Rule 62.
Rule 62-ன்படி, ஒவ்வொரு காலாண்டுக்கும் FORM GST CMP-08 (காலாண்டு முடிந்த அடுத்த மாதம் 18-ம் தேதிக்குள்), ஆண்டுக்கு ஒரு முறை FORM GSTR-4 (FY 2024-25 முதல், நிதியாண்டு முடிந்த பிறகு வரும் ஜூன் 30-க்குள்).
8. Can a goods trader under composition also supply services?
Yes, within a limit. Services can be supplied up to 10% of the previous year's turnover in the State or ₹5 lakh, whichever is higher.
ஆம், ஒரு வரம்புக்குள். முந்தைய ஆண்டின் மாநில turnover-ல் 10% அல்லது ₹5 லட்சம், இதில் எது அதிகமோ அதுவரை சேவைகள் வழங்கலாம்.
9. Who cannot opt for the composition scheme?
Manufacturers of ice cream, pan masala, tobacco products and aerated water, casual taxable persons, non-resident taxable persons and anyone making inter-State outward supplies. If several registrations share one PAN, all must opt together.
Ice cream, pan masala, tobacco பொருட்கள், aerated water உற்பத்தியாளர்கள், casual taxable persons, non-resident taxable persons, வெளி மாநிலங்களுக்கு விற்பனை செய்பவர்கள் ஆகியோர் தேர்வு செய்ய முடியாது. ஒரே PAN-ல் பல registrations இருந்தால் அனைத்தும் சேர்ந்தே தேர்வு செய்ய வேண்டும்.
10. Where can I get composition scheme help near me in Tambaram, Chennai?
Phoenix Tax Consultant™ in Tambaram, Chennai helps with GST registration, choosing between regular and composition GST, CMP-08 and GSTR-4 filing. Call 99403 49819 or WhatsApp 88072 58797.
Tambaram, Chennai-ல் உள்ள Phoenix Tax Consultant™, GST registration, regular அல்லது composition தேர்வு, CMP-08 மற்றும் GSTR-4 தாக்கல் ஆகியவற்றில் உதவுகிறது. 99403 49819-ல் அழைக்கவும் அல்லது 88072 58797-ல் WhatsApp செய்யவும்.
Official sources | அதிகாரப்பூர்வ ஆதாரங்கள்
- Section 10, CGST Act – Composition levy (taxinformation.cbic.gov.in)
- Rule 7, CGST Rules – Rate of composition levy (taxinformation.cbic.gov.in)
- Rule 62, CGST Rules – CMP-08 and GSTR-4 (taxinformation.cbic.gov.in)
- Notification 14/2019-Central Tax – ₹1.5 crore limit (gstcouncil.gov.in)
- 56th GST Council recommendations – 5%, 18%, 40% rates (pib.gov.in)
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration