 Phoenix Tax Consultant™ November 12, 2026
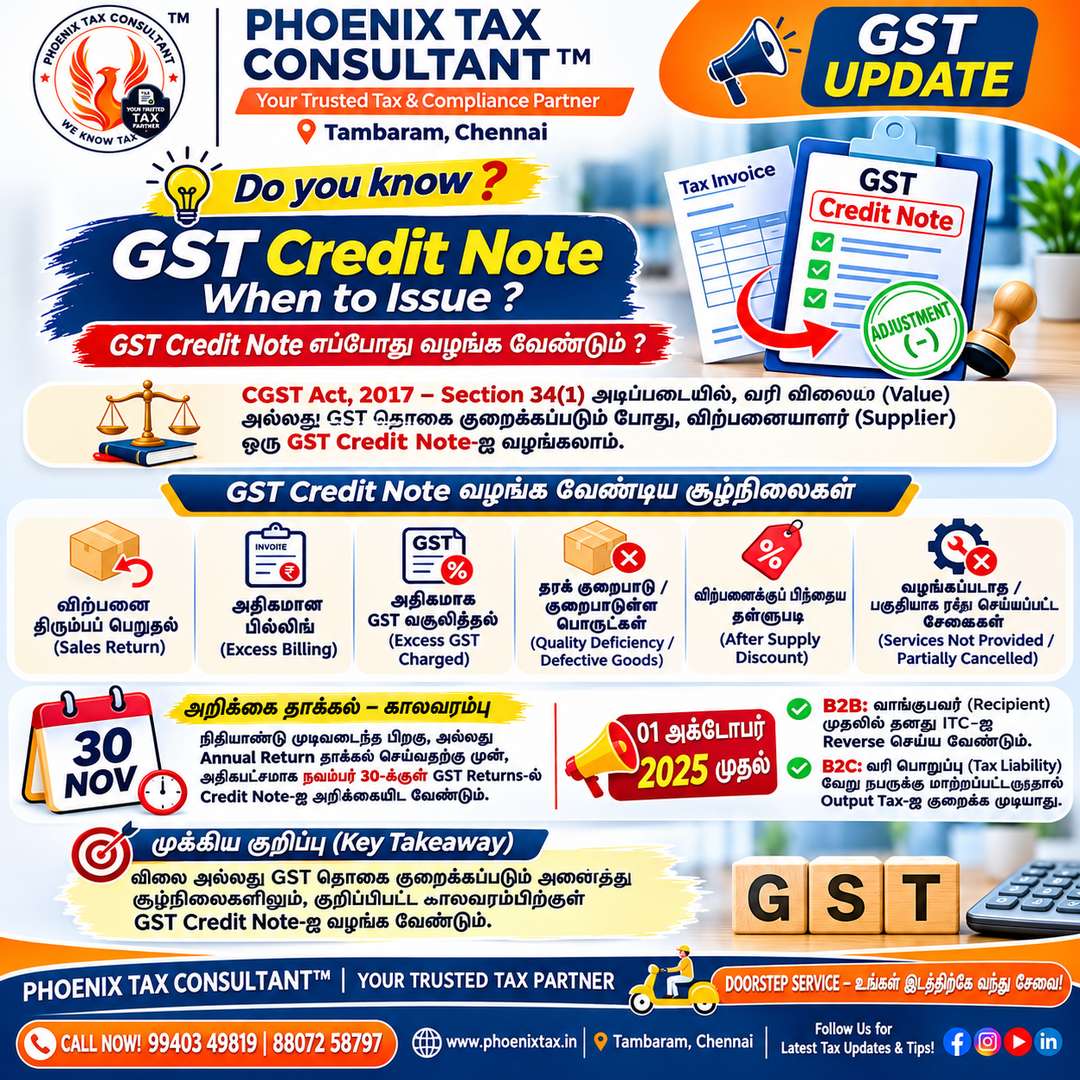
Quick Answer: A GST credit note is issued by the supplier under Section 34 of the CGST Act when the invoice value/tax is higher than actual, goods are returned, or goods/services are found deficient. It must be declared in the return by 30 November after the end of the financial year (or the annual return date, if earlier). From 1 October 2025, the supplier gets tax reduction only if the registered buyer has reversed the ITC.
விரைவு பதில்: Invoice மதிப்பு/வரி அதிகமாக இருந்தால், சரக்கு திரும்ப வந்தால், அல்லது சரக்கு/சேவை குறைபாடாக இருந்தால் supplier Section 34-ன் கீழ் credit note வழங்கலாம். நிதியாண்டு முடிந்த பின் வரும் 30 நவம்பர் (அல்லது annual return தேதி – எது முந்தையதோ) வரை return-ல் காட்ட வேண்டும். 1.10.2025 முதல், வாங்குபவர் ITC-ஐ reverse செய்தால் மட்டுமே supplier-க்கு வரி குறைப்பு கிடைக்கும்.
Credit Note in GST – At a Glance
| Point | Details |
|---|---|
| Law | Section 34(1) & 34(2), CGST Act, 2017 |
| Who issues | Registered supplier, to the recipient |
| When | Excess value/tax in invoice; goods returned; goods/services found deficient |
| Time limit | 30 November following end of FY, or annual return filing date – whichever is earlier |
| B2B condition (from 01.10.2025) | Registered recipient must reverse ITC attributable to the credit note |
| Other cases (B2C) | Incidence of tax should not have been passed on to any other person |
| Post-supply discount (Sec 15(3)(b)) | Inserted by Finance Act 2026 – effective date yet to be notified |
When Can You Issue a GST Credit Note?
- Taxable value or tax charged in the tax invoice is more than the actual value/tax payable.
- Goods supplied are returned by the recipient.
- Goods or services supplied are found to be deficient.
One credit note can cover one or more invoices of the same financial year.
தமிழில்: GST-ல் credit note வழங்கக்கூடிய சூழ்நிலைகள் மூன்று மட்டுமே – (1) Tax invoice-ல் காட்டிய மதிப்பு அல்லது வரி, உண்மையில் செலுத்த வேண்டியதை விட அதிகமாக இருக்கும்போது; (2) வாங்குபவர் சரக்கை திரும்ப அனுப்பும்போது; (3) வழங்கிய சரக்கு அல்லது சேவை குறைபாடாக (deficient) இருக்கும்போது. ஒரே நிதியாண்டின் பல invoice-களுக்கு ஒரே credit note வழங்கலாம்.
Time Limit – 30 November Rule
Credit notes for supplies of FY 2025-26 must be declared in returns not later than 30 November 2026, or the date of filing the FY 2025-26 annual return, whichever is earlier. After this, the supplier cannot reduce output tax for that credit note.
தமிழில்: FY 2025-26 விற்பனைக்கான credit note-களை 30 நவம்பர் 2026-க்குள், அல்லது FY 2025-26 annual return தாக்கல் செய்யும் தேதிக்குள் – இவற்றில் எது முந்தையதோ அதற்குள் – return-ல் காட்ட வேண்டும். இந்த தேதிக்குப் பிறகு அந்த credit note-க்கு வரி குறைப்பு பெற முடியாது.
Reversal of Input Tax Credit on Credit Note – Rule from 1 October 2025
- B2B: Supplier’s output tax is reduced only if the registered buyer has reversed the input tax credit (ITC) on that credit note (if availed).
- Other cases: Reduction allowed only if tax incidence has not been passed on to any other person.
This proviso to Section 34(2) was substituted by section 126 of the Finance (No. 7) Act, 2025, effective 01.10.2025.
தமிழில்: 1.10.2025 முதல், registered வாங்குபவர் அந்த credit note-க்குரிய input tax credit-ஐ reverse செய்தால் மட்டுமே supplier-ன் output tax குறையும். பதிவு இல்லாத வாங்குபவர்கள் (B2C) விஷயத்தில், அந்த வரிச்சுமை வேறு நபருக்கு மாற்றப்படவில்லை என்றால் மட்டுமே குறைப்பு கிடைக்கும். எனவே B2B வாடிக்கையாளர்களிடம் ITC reversal-ஐ உறுதிசெய்து கொள்ளுங்கள்.
Credit Note vs Debit Note
| Credit Note – Sec 34(1) | Debit Note – Sec 34(3) |
|---|---|
| Value/tax charged is more than actual | Value/tax charged is less than actual |
| Reduces supplier’s tax liability (subject to conditions) | Increases supplier’s tax liability |
| Time limit – 30 November rule applies | Declare in the month of issue |
Read more: Debit Note in GST – when to issue under Section 34(3).
தமிழில்: Credit note மதிப்பு/வரியைக் குறைக்கும்; debit note (Section 34(3)) மதிப்பு/வரியை அதிகரிக்கும். Debit note-ஐ வழங்கிய மாதத்தின் return-லேயே காட்ட வேண்டும்.
Practical Steps for Businesses
- Issue the credit note with the original invoice reference.
- Report it in GSTR-1 of the month/quarter of issue.
- Inform the B2B buyer to reverse the ITC on time.
- Reconcile before 30 November to avoid losing the adjustment.
தமிழில்: (1) அசல் invoice எண்ணுடன் credit note வழங்குங்கள். (2) வழங்கிய மாதம்/காலாண்டின் GSTR-1-ல் காட்டுங்கள். (3) B2B வாங்குபவரிடம் ITC reverse செய்யச் சொல்லுங்கள். (4) 30 நவம்பருக்கு முன் reconciliation முடியுங்கள். Tambaram, Chennai-ல் உங்கள் அருகில் உள்ள GST consultant-ஆக Phoenix Tax Consultant™ இதை முழுமையாக கவனித்துக்கொள்ளும்.
Related Services – Phoenix Tax Consultant™
- Debit Note in GST – When to Issue & Example
- GST Return Filing in Tambaram, Chennai
- GST Registration in Tambaram, Chennai
- Tax Consultant near me in Tambaram
- How to Make a GST Payment
- TDS under GST
Official References
FAQ – Credit Note in GST
1. What is a GST credit note?
A document issued by the supplier under Section 34 to reduce the value or tax of an earlier tax invoice.
முந்தைய tax invoice-ன் மதிப்பு அல்லது வரியைக் குறைக்க, Section 34-ன் கீழ் supplier வழங்கும் ஆவணம்.
2. Who can issue a credit note under GST?
Only the registered supplier who issued the original tax invoice.
அசல் tax invoice வழங்கிய registered supplier மட்டுமே.
3. When should a credit note be issued?
When value/tax charged is excess, goods are returned, or goods/services are found deficient.
மதிப்பு/வரி அதிகமாக வசூலித்தால், சரக்கு திரும்ப வந்தால், அல்லது சரக்கு/சேவை குறைபாடாக இருந்தால்.
4. What is the last date to declare a credit note for FY 2025-26?
30 November 2026, or the annual return filing date for FY 2025-26, whichever is earlier.
30 நவம்பர் 2026, அல்லது FY 2025-26 annual return தாக்கல் தேதி – எது முந்தையதோ.
5. What changed from 1 October 2025?
Supplier’s tax reduction is allowed only if the registered recipient has reversed the related ITC.
Registered வாங்குபவர் தொடர்புடைய ITC-ஐ reverse செய்தால் மட்டுமே supplier-க்கு வரி குறைப்பு.
6. What about credit notes to unregistered buyers (B2C)?
Reduction is allowed only if the tax incidence has not been passed on to any other person.
வரிச்சுமை வேறு நபருக்கு மாற்றப்படவில்லை என்றால் மட்டுமே குறைப்பு கிடைக்கும்.
7. Can one credit note cover many invoices?
Yes. One or more credit notes can be issued for supplies made in a financial year.
ஆம். ஒரு நிதியாண்டின் விற்பனைகளுக்கு ஒன்று அல்லது பல credit note வழங்கலாம்.
8. Can a credit note be issued for post-sale discount?
A specific ground for Section 15(3)(b) discounts was inserted by Finance Act 2026, but its effective date is yet to be notified.
Section 15(3)(b) discount-க்கான விதி Finance Act 2026-ல் சேர்க்கப்பட்டது; அமலுக்கு வரும் தேதி இன்னும் அறிவிக்கப்படவில்லை.
9. What is the difference between a credit note and a debit note?
Credit note reduces value/tax; debit note (Section 34(3)) increases it.
Credit note மதிப்பு/வரியைக் குறைக்கும்; debit note (Section 34(3)) அதிகரிக்கும்.
10. Is there a GST consultant near me in Tambaram for credit note issues?
Yes. Phoenix Tax Consultant™ in Tambaram, Chennai handles GST returns, credit note reconciliation and ITC matching.
ஆம். Tambaram, Chennai-ல் Phoenix Tax Consultant™ GST return, credit note reconciliation, ITC matching செய்கிறது. அழைக்கவும்: 99403 49819.
Need Help with GST Credit Notes? | GST Credit Note உதவி வேண்டுமா?
Phoenix Tax Consultant™ – ISO 9001:2015 Certified, Tambaram, Chennai. GST return filing, credit note & ITC reconciliation.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
No. 10A, 2nd Floor, Rajendra Building, Duraisamy Pillai Street, West Tambaram, Chennai – 600045
Related services: LUT Filing | GST Registration | Tax Consultant in Tambaram, Chennai
Official reference: Section 16, IGST Act (CBIC) | LUT FAQ – GST Portal | CBIC GST
