 Phoenix Tax Consultant™ November 12, 2026
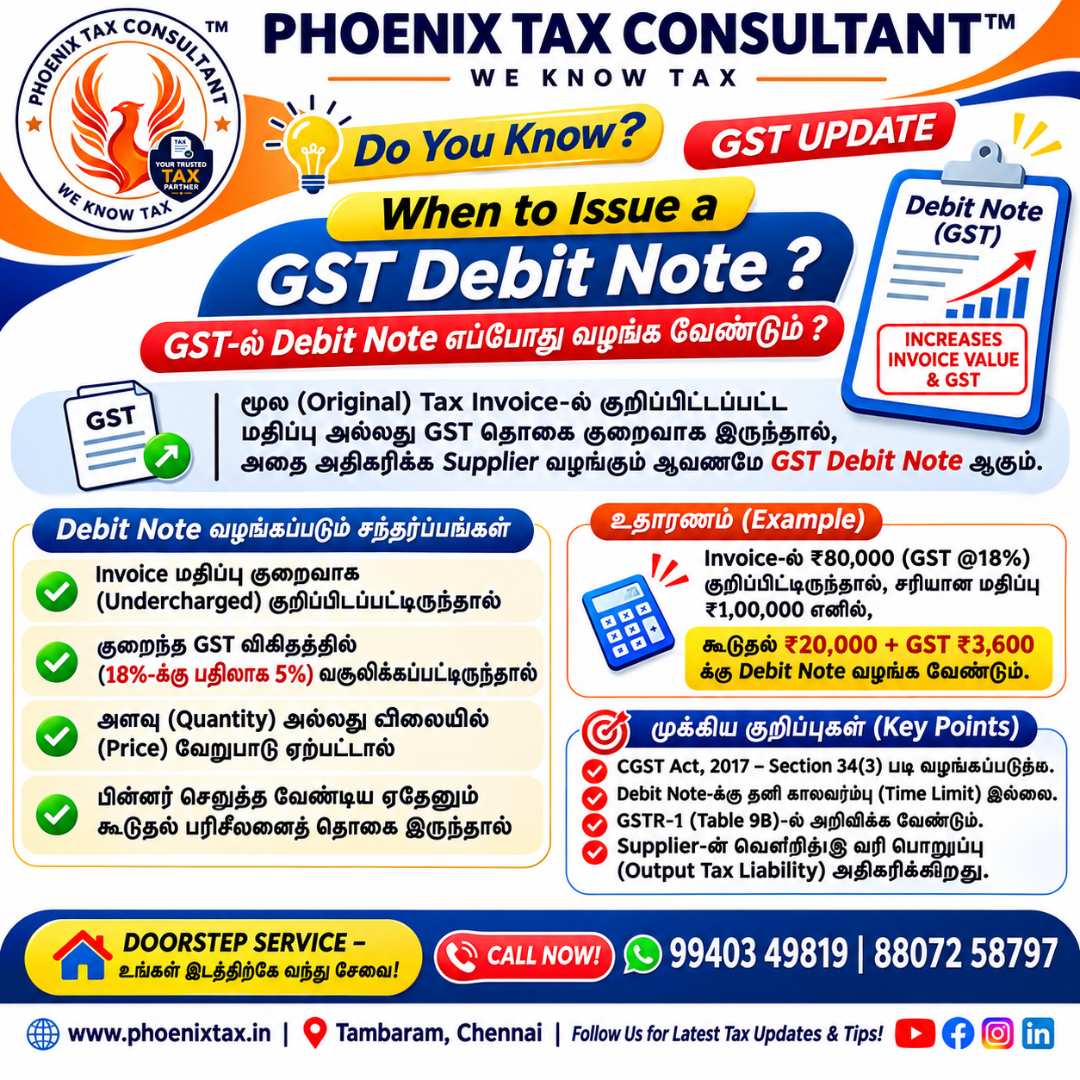
Quick Answer: A GST debit note is issued by the supplier under Section 34(3) of the CGST Act when the taxable value or GST charged in the original tax invoice is less than the actual amount payable. It must be declared in the return for the month in which it is issued, and it increases the supplier’s output tax. A supplementary invoice is also treated as a debit note.
விரைவு பதில்: அசல் tax invoice-ல் காட்டிய மதிப்பு அல்லது GST, உண்மையில் செலுத்த வேண்டியதை விடக் குறைவாக இருந்தால், Section 34(3)-ன் கீழ் supplier வழங்கும் ஆவணமே GST debit note. வழங்கிய மாதத்தின் return-லேயே காட்ட வேண்டும்; இது supplier-ன் output tax-ஐ அதிகரிக்கும். Supplementary invoice-ம் debit note-ஆகவே கருதப்படும்.
Debit Note in GST – At a Glance
| Point | Details |
|---|---|
| Law | Section 34(3) & 34(4), CGST Act, 2017 |
| Who issues | Registered supplier, to the recipient |
| When | Taxable value or tax charged in invoice is less than actual |
| Includes | Supplementary invoice (Explanation to Section 34) |
| Return | Declare in the return for the month of issue – GSTR-1 (Table 9B) |
| Effect | Increases supplier’s output tax liability |
When to Issue a GST Debit Note?
- Invoice value was undercharged.
- GST was charged at a lower rate than applicable (e.g. 5% charged instead of 18%).
- Price was revised upward after the invoice was issued.
- Quantity or price difference found later that increases the value.
தமிழில்: (1) Invoice மதிப்பு குறைவாகக் குறிப்பிடப்பட்டிருந்தால்; (2) சரியான விகிதத்தை விடக் குறைந்த விகிதத்தில் GST வசூலித்திருந்தால் (எ.கா., 18%-க்கு பதிலாக 5%); (3) invoice-க்குப் பின் விலை உயர்த்தப்பட்டால்; (4) பின்னர் அளவு அல்லது விலையில் வேறுபாடு கண்டறியப்பட்டு மதிப்பு அதிகரித்தால் – debit note வழங்க வேண்டும்.
Example
Invoice issued for ₹80,000 + GST @18%, but the correct value is ₹1,00,000. The supplier issues a debit note for ₹20,000 + GST ₹3,600.
தமிழில்: Invoice-ல் ₹80,000 (GST 18%) எனக் குறிப்பிட்டு, சரியான மதிப்பு ₹1,00,000 எனில், கூடுதல் ₹20,000 + GST ₹3,600-க்கு debit note வழங்க வேண்டும்.
Time Limit and Return Reporting
Section 34(4) requires the debit note to be declared in the return for the month in which it is issued, and the tax liability is adjusted accordingly. Unlike credit notes, there is no 30 November outer limit in Section 34 for debit notes.
தமிழில்: Section 34(4) படி, debit note வழங்கிய மாதத்தின் return-லேயே காட்ட வேண்டும். Credit note-க்கு உள்ள 30 நவம்பர் வரம்பு Section 34-ல் debit note-க்கு இல்லை.
Debit Note vs Credit Note
| Debit Note – Sec 34(3) | Credit Note – Sec 34(1) |
|---|---|
| Value/tax charged is less than actual | Value/tax charged is more than actual, goods returned or deficient |
| Increases output tax | Reduces output tax (subject to ITC reversal by recipient from 01.10.2025) |
| Declare in month of issue | 30 November / annual return date, whichever earlier |
தமிழில்: Debit note வரியை அதிகரிக்கும்; credit note வரியைக் குறைக்கும். Credit note விவரங்களுக்கு கீழே உள்ள எங்கள் Credit Note கட்டுரையைப் பாருங்கள்.
Practical Steps for Businesses
- Issue the debit note quoting the original invoice details.
- Report it in GSTR-1 of the month/quarter of issue.
- Pay the additional tax through GSTR-3B of the same period.
- Share the debit note with the buyer for ITC matching.
தமிழில்: (1) அசல் invoice விவரத்துடன் debit note வழங்குங்கள். (2) அதே மாதம்/காலாண்டின் GSTR-1-ல் காட்டுங்கள். (3) கூடுதல் வரியை GSTR-3B மூலம் செலுத்துங்கள். (4) வாங்குபவருக்கு ITC பொருத்தத்துக்காக அனுப்புங்கள். Tambaram, Chennai-ல் உங்கள் அருகில் உள்ள GST consultant-ஆக Phoenix Tax Consultant™ இதை முழுமையாக கவனித்துக்கொள்ளும்.
Related Services – Phoenix Tax Consultant™
- Credit Note in GST – Time Limit & ITC Reversal
- GST Return Filing in Tambaram, Chennai
- GST Registration in Tambaram, Chennai
- Tax Consultant near me in Tambaram
- How to Make a GST Payment
Official References
FAQ – Debit Note in GST
1. What is a debit note in GST?
A document issued by the supplier under Section 34(3) of the CGST Act when the taxable value or tax charged in the tax invoice is less than the actual value or tax payable.
Tax invoice-ல் காட்டிய மதிப்பு அல்லது வரி, உண்மையில் செலுத்த வேண்டியதை விடக் குறைவாக இருந்தால், Section 34(3)-ன் கீழ் supplier வழங்கும் ஆவணம்.
2. Who issues a GST debit note?
The registered supplier who issued the original tax invoice issues it to the recipient.
அசல் tax invoice வழங்கிய registered supplier, வாங்குபவருக்கு வழங்குவார்.
3. When should a debit note be issued?
When the invoice value is undercharged, GST is charged at a lower rate than applicable, or the price is revised upward after the invoice.
Invoice மதிப்பு குறைவாக இருந்தால், சரியான விகிதத்தை விடக் குறைந்த விகிதத்தில் GST வசூலித்தால், அல்லது invoice-க்குப் பின் விலை உயர்த்தப்பட்டால்.
4. Is a supplementary invoice the same as a debit note?
Yes. As per the Explanation to Section 34, the expression “debit note” includes a supplementary invoice.
ஆம். Section 34-ன் Explanation படி “debit note” என்பதில் supplementary invoice-ம் அடங்கும்.
5. Is there a time limit to issue a debit note?
Section 34(4) has no outer time limit like the 30 November rule for credit notes; the debit note must be declared in the return for the month in which it is issued.
Credit note-க்கு உள்ள 30 நவம்பர் வரம்பு போன்றது debit note-க்கு இல்லை; வழங்கிய மாதத்தின் return-லேயே காட்ட வேண்டும்.
6. Where is a debit note reported in GST returns?
In GSTR-1 (Table 9B – credit/debit notes) of the month or quarter of issue, and the extra tax is paid through GSTR-3B.
வழங்கிய மாதம்/காலாண்டின் GSTR-1 (Table 9B)-ல் காட்டி, கூடுதல் வரியை GSTR-3B மூலம் செலுத்த வேண்டும்.
7. Does a debit note increase tax liability?
Yes. It increases the supplier’s output tax liability.
ஆம். Supplier-ன் output tax பொறுப்பு அதிகரிக்கும்.
8. Can one debit note cover many invoices?
Yes. One or more debit notes can be issued for supplies made in a financial year.
ஆம். ஒரு நிதியாண்டின் விற்பனைகளுக்கு ஒன்று அல்லது பல debit note வழங்கலாம்.
9. What is the difference between a debit note and a credit note?
A debit note (Section 34(3)) increases value/tax; a credit note (Section 34(1)) reduces it and has the 30 November time limit.
Debit note மதிப்பு/வரியை அதிகரிக்கும்; credit note குறைக்கும், அதற்கு 30 நவம்பர் கால வரம்பு உண்டு.
10. Is there a GST consultant near me in Tambaram for debit note and GST return work?
Yes. Phoenix Tax Consultant™ in Tambaram, Chennai handles debit/credit notes, GSTR-1, GSTR-3B and reconciliation.
ஆம். Tambaram, Chennai-ல் Phoenix Tax Consultant™ debit/credit note, GSTR-1, GSTR-3B, reconciliation செய்கிறது. அழைக்கவும்: 99403 49819.
Need Help with GST Debit Notes? | GST Debit Note உதவி வேண்டுமா?
Phoenix Tax Consultant™ – ISO 9001:2015 Certified, Tambaram, Chennai. GST return filing, debit/credit note & reconciliation.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
No. 10A, 2nd Floor, Rajendra Building, Duraisamy Pillai Street, West Tambaram, Chennai – 600045
Related services: LUT Filing | GST Registration | Tax Consultant in Tambaram, Chennai
Official reference: Section 16, IGST Act (CBIC) | LUT FAQ – GST Portal | CBIC GST
