 Phoenix Tax Consultant™ November 15, 2026
One PAN, two categories? From 1 Nov 2026 the GST Portal no longer lets you pick Section 10(1) and Section 10(2A) together. Here is how the composition scheme works now.
ஒரே PAN-ல் இரண்டு பிரிவுகளா? 1 Nov 2026 முதல் GST Portal-ல் பிரிவு 10(1), 10(2A) இரண்டையும் ஒரே நேரத்தில் தேர்வு செய்ய முடியாது. கலவைத் திட்டம் இப்போது எப்படி செயல்படுகிறது என்பதைப் பாருங்கள்.
Quick Answer: The GST Composition Scheme (Section 10, CGST Act) lets eligible small taxpayers pay a fixed 1%, 5% or 6% of turnover, with a limit of ₹1.5 crore (goods) or ₹50 lakh (Section 10(2A) services), but without Input Tax Credit.
Near me: Looking for composition scheme in GST near me? Phoenix Tax Consultant™ helps businesses in Tambaram, Chennai – call 99403 49819 / 88072 58797.
விரைவு பதில்: GST கலவைத் திட்டத்தில் (பிரிவு 10) தகுதியுள்ள சிறு வணிகர்கள் விற்றுமுதலில் 1%, 5% அல்லது 6% நிலையான வரி செலுத்தலாம்; வரம்பு ₹1.5 கோடி (பொருட்கள்) அல்லது ₹50 லட்சம் (பிரிவு 10(2A) சேவைகள்); ITC கிடையாது.
அருகில் உதவி: Composition scheme in GST near me தேடுகிறீர்களா? தாம்பரம், சென்னையில் Phoenix Tax Consultant™-ஐ 99403 49819 / 88072 58797 எண்களில் அழைக்கவும்.
What is the Composition Scheme in GST?
Section 10 of the CGST Act (CBIC text) allows a registered person within the turnover limit to pay tax at a prescribed rate on turnover instead of regular GST. It is voluntary and aimed at small and medium traders.
GST கலவைத் திட்டம் என்றால் என்ன?
CGST சட்டம் பிரிவு 10-ன்படி, வரம்புக்குள் உள்ள பதிவு பெற்ற நபர், வழக்கமான GST-க்குப் பதிலாக விற்றுமுதலில் குறிப்பிட்ட சதவீதத்தில் வரி செலுத்தலாம். இது விருப்பத் திட்டம்; சிறு, நடுத்தர வணிகங்களுக்கு ஏற்றது.
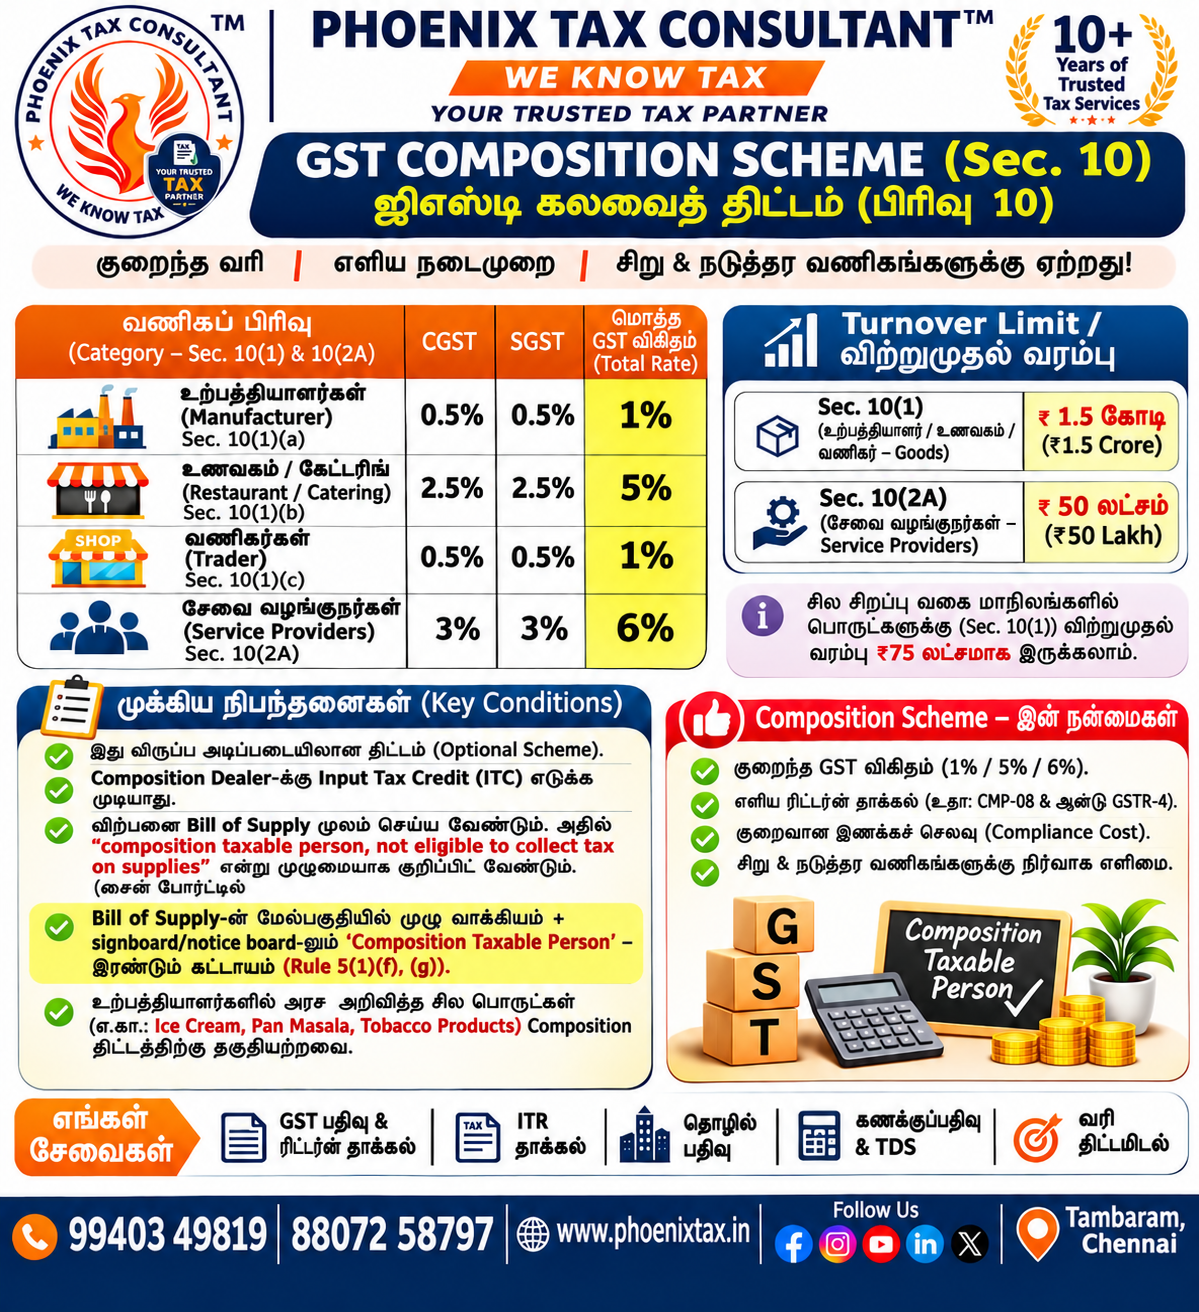
Composition Scheme Rates (CGST + SGST)
கலவைத் திட்ட வரி விகிதங்கள்
| Category / பிரிவு | Section | CGST | SGST | Total / மொத்தம் |
|---|---|---|---|---|
| Manufacturer / உற்பத்தியாளர் | 10(1)(a) | 0.5% | 0.5% | 1% |
| Restaurant / Catering / உணவகம் | 10(1)(b) | 2.5% | 2.5% | 5% |
| Trader / வணிகர் | 10(1)(c) | 0.5% | 0.5% | 1% |
| Service Provider / சேவை வழங்குநர் | 10(2A) | 3% | 3% | 6% |
Rates are as per Rule 7, CGST Rules. / விகிதங்கள் CGST விதிகள் Rule 7-ன்படி.
Turnover Limit for Composition Scheme in GST
Section 10(1) (goods, restaurants): ₹1.5 crore, as notified in Notification 14/2019-Central Tax dated 07.03.2019 (PIB). Section 10(2A) (services): ₹50 lakh. Some special category States have a lower limit for goods. The limit is checked on PAN-based aggregate turnover of the preceding financial year.
விற்றுமுதல் வரம்பு
பிரிவு 10(1) (பொருட்கள், உணவகம்): ₹1.5 கோடி – Notification 14/2019-Central Tax (07.03.2019). பிரிவு 10(2A) (சேவைகள்): ₹50 லட்சம். சில சிறப்பு வகை மாநிலங்களில் பொருட்களுக்கு வரம்பு குறைவு. முந்தைய நிதியாண்டின் PAN அடிப்படையிலான மொத்த விற்றுமுதல் கணக்கிடப்படும்.
Key Conditions of the Composition Scheme
- No Input Tax Credit on purchases; no tax collected from customers.
- Issue a Bill of Supply with “composition taxable person, not eligible to collect tax on supplies” at the top.
- Show “composition taxable person” on every notice or signboard at each place of business (Rule 5(1)(f), (g)).
- File CMP-08 (quarterly payment) and GSTR-4 (annual return).
- Option lapses when turnover crosses the limit (Section 10(3)); withdrawal is through Form CMP-04.
முக்கிய நிபந்தனைகள்
- கொள்முதலுக்கு ITC கிடையாது; வாடிக்கையாளரிடம் வரி வசூலிக்கக் கூடாது.
- Bill of Supply-ன் மேல்பகுதியில் “composition taxable person, not eligible to collect tax on supplies” என்று எழுத வேண்டும்.
- ஒவ்வொரு வணிக இடத்திலும் notice/signboard-ல் “composition taxable person” என்று காட்ட வேண்டும் (Rule 5(1)(f), (g)).
- CMP-08 (காலாண்டு வரி செலுத்த), GSTR-4 (ஆண்டு ரிட்டர்ன்) தாக்கல் செய்ய வேண்டும்.
- விற்றுமுதல் வரம்பைத் தாண்டினால் தேர்வு காலாவதியாகும் (பிரிவு 10(3)); விலகல் Form CMP-04 மூலம்.
Who Cannot Opt for Composition?
Manufacturers of ice cream and other edible ice, pan masala, and tobacco and manufactured tobacco substitutes are not eligible (GST Portal guide).
யார் சேர முடியாது?
Ice cream மற்றும் பிற edible ice, Pan Masala, புகையிலை மற்றும் புகையிலைப் பொருட்கள் உற்பத்தியாளர்கள் இத்திட்டத்தில் சேர முடியாது.
How to Opt for Composition Scheme in GST
New registrations: choose composition in Form REG-01. Existing regular taxpayers: file Form CMP-02 on the GST portal before the financial year begins. See GST registration in Tambaram, Chennai for help with the process.
கலவைத் திட்டத்தில் எப்படி சேருவது?
புதிய பதிவு: Form REG-01-ல் தேர்வு செய்யவும். ஏற்கனவே regular taxpayer: நிதியாண்டு தொடங்கும் முன் GST portal-ல் Form CMP-02 தாக்கல் செய்யவும். உதவிக்கு தாம்பரம், சென்னை GST பதிவு பக்கத்தைப் பாருங்கள்.
New: Option A and Option B on the GST Portal (1 Nov 2026)
The GST Portal advisory dated 1 Nov 2026 (gst.gov.in) introduced a new category for Section 10(2A). Option A lets you select multiple Section 10(1) categories; Option B is the single Section 10(2A) category. Both cannot be selected together. Category changes can now be made through Form REG-14; read our guide on REG-14 amendment and the GST changes from 1 November 2026.
புதிய மாற்றம்: Option A, Option B (1 Nov 2026)
1 Nov 2026 GST Portal advisory பிரிவு 10(2A)-க்கு புதிய பிரிவை அறிமுகப்படுத்தியது. Option A-ல் பிரிவு 10(1) பிரிவுகளில் பலவற்றைத் தேர்வு செய்யலாம்; Option B பிரிவு 10(2A) மட்டும். இரண்டையும் ஒரே நேரத்தில் தேர்வு செய்ய முடியாது. பிரிவை மாற்ற Form REG-14 பயன்படுத்தலாம். மேலும் அறிய REG-14 திருத்தம், 1 Nov 2026 GST மாற்றங்கள் கட்டுரைகளைப் பாருங்கள்.
Section 10(2A) Composition: Key Points and PAN Check
Option B (Section 10(2A)) is for a registered person who is not eligible under Section 10(1) and (2), such as a service provider or mixed supplier (PIB). The previous financial year’s PAN-based aggregate turnover must not exceed ₹50 lakh, tax is 6% (3% CGST + 3% SGST), there is no ITC, and no tax can be collected from customers.
If you are already a taxpayer, check the category selected on your registration. When you hold more than one registration on the same PAN, the portal compares the categories on your existing composition registrations with the one chosen in CMP-02 and asks you to make them the same; turnover is checked across all registrations on that PAN (GST Portal guide).
பிரிவு 10(2A): முக்கிய குறிப்புகள் மற்றும் PAN சரிபார்ப்பு
Option B (பிரிவு 10(2A)) பிரிவு 10(1), (2)-ன் கீழ் தகுதி இல்லாத சேவை வழங்குநர்கள், கலப்பு வழங்குநர்களுக்கானது. முந்தைய நிதியாண்டின் PAN அடிப்படையிலான மொத்த விற்றுமுதல் ₹50 லட்சத்துக்கு மிகாமல் இருக்க வேண்டும்; வரி 6% (3% CGST + 3% SGST); ITC கிடையாது; வாடிக்கையாளரிடம் வரி வசூலிக்க முடியாது.
ஏற்கனவே பதிவு பெற்றவர்கள், தங்கள் பதிவில் தேர்வான பிரிவைச் சரிபார்க்கவும். ஒரே PAN-ல் ஒன்றுக்கு மேற்பட்ட பதிவுகள் இருந்தால், CMP-02-ல் தேர்வு செய்த பிரிவும் ஏற்கனவே உள்ள composition பதிவுகளின் பிரிவும் ஒன்றாக இருக்க வேண்டும் என்று portal கேட்கும்; விற்றுமுதல் அந்த PAN-ல் உள்ள அனைத்துப் பதிவுகளையும் சேர்த்துச் சரிபார்க்கப்படும்.
Is the Composition Scheme Right for You?
It suits small traders and restaurants with low turnover and little ITC. If most of your buyers are GST-registered businesses who need ITC, regular GST may work better. Keep your returns on time with our GST return filing in Tambaram, Chennai service and the tax and compliance calendar.
இத்திட்டம் உங்களுக்கு ஏற்றதா?
குறைந்த விற்றுமுதல், குறைவான ITC உள்ள சிறு வணிகர்கள், உணவகங்களுக்கு ஏற்றது. உங்கள் வாடிக்கையாளர்களில் பெரும்பாலோர் ITC தேவைப்படும் GST பதிவு பெற்ற வணிகங்கள் என்றால் வழக்கமான GST சிறந்ததாக இருக்கலாம். ரிட்டர்ன்களை நேரத்தில் தாக்கல் செய்ய GST ரிட்டர்ன் தாக்கல் – தாம்பரம், சென்னை, வரி இணக்கக் காலண்டர் பயன்படுத்துங்கள்.
Composition Scheme in GST Near Me – Tambaram, Chennai
Phoenix Tax Consultant™ helps traders, restaurants, manufacturers and service providers in Tambaram, Chromepet, Pallavaram, Selaiyur, Perungalathur and across Chennai with composition scheme registration, CMP-02 / CMP-04, CMP-08 and GSTR-4 filing. Call 99403 49819 / 88072 58797.
அருகிலுள்ள GST கலவைத் திட்ட உதவி – தாம்பரம், சென்னை
தாம்பரம், குரோம்பேட்டை, பல்லாவரம், சேலையூர், பெருங்களத்தூர் மற்றும் சென்னை முழுவதும் வணிகர்கள், உணவகங்கள், உற்பத்தியாளர்கள், சேவை வழங்குநர்களுக்கு கலவைத் திட்டப் பதிவு, CMP-02 / CMP-04, CMP-08, GSTR-4 தாக்கல் ஆகியவற்றில் Phoenix Tax Consultant™ உதவுகிறது. 99403 49819 / 88072 58797.
GST Composition Scheme FAQs / அடிக்கடி கேட்கப்படும் கேள்விகள்
1. What is the GST Composition Scheme?
An optional scheme under Section 10 of the CGST Act where eligible small taxpayers pay tax at a fixed percentage of turnover instead of regular GST, with simpler compliance.
GST கலவைத் திட்டம் என்றால் என்ன?
CGST சட்டம் பிரிவு 10-ன் கீழ் உள்ள விருப்பத் திட்டம். தகுதியுள்ள சிறு வணிகர்கள் வழக்கமான GST-க்குப் பதிலாக விற்றுமுதலில் ஒரு நிலையான சதவீதம் வரி செலுத்தலாம்; இணக்க நடைமுறைகள் எளிது.
2. What are the composition rates?
Manufacturers and traders: 1% (0.5% CGST + 0.5% SGST). Restaurants/catering: 5% (2.5% + 2.5%). Section 10(2A) service providers: 6% (3% + 3%).
கலவைத் திட்ட வரி விகிதங்கள் என்ன?
உற்பத்தியாளர்கள், வணிகர்கள்: 1% (0.5% CGST + 0.5% SGST). உணவகம்/கேட்டரிங்: 5% (2.5% + 2.5%). பிரிவு 10(2A) சேவை வழங்குநர்கள்: 6% (3% + 3%).
3. What is the turnover limit?
Rs 1.5 crore for Section 10(1) goods suppliers and Rs 50 lakh for Section 10(2A) service providers. Some special category States have a lower goods limit.
விற்றுமுதல் வரம்பு எவ்வளவு?
பிரிவு 10(1) பொருள் வழங்குநர்களுக்கு ₹1.5 கோடி; பிரிவு 10(2A) சேவை வழங்குநர்களுக்கு ₹50 லட்சம். சில சிறப்பு வகை மாநிலங்களில் பொருட்களுக்கு வரம்பு குறைவாக இருக்கும்.
4. Can a composition dealer claim Input Tax Credit?
No. A composition taxpayer cannot claim ITC on purchases.
Composition dealer Input Tax Credit எடுக்கலாமா?
முடியாது. கலவைத் திட்டத்தில் உள்ளவர் கொள்முதலுக்கு ITC எடுக்க முடியாது.
5. Can a composition dealer collect GST from customers?
No. Supplies are made on a Bill of Supply, not a tax invoice, and no tax can be collected from customers.
வாடிக்கையாளர்களிடம் GST வசூலிக்கலாமா?
கூடாது. Tax invoice அல்ல, Bill of Supply மூலமே விற்பனை செய்ய வேண்டும்; வாடிக்கையாளரிடம் வரி வசூலிக்கக் கூடாது.
6. What must be written on the Bill of Supply and signboard?
The words "composition taxable person, not eligible to collect tax on supplies" at the top of every Bill of Supply, and "composition taxable person" on every notice or signboard at each place of business (Rule 5(1)(f) and (g)).
Bill of Supply, signboard-ல் என்ன எழுத வேண்டும்?
ஒவ்வொரு Bill of Supply-ன் மேல்பகுதியில் “composition taxable person, not eligible to collect tax on supplies” என்றும், ஒவ்வொரு வணிக இடத்திலுள்ள notice/signboard-ல் “composition taxable person” என்றும் எழுத வேண்டும் (Rule 5(1)(f), (g)).
7. Which goods manufacturers cannot opt?
Manufacturers of ice cream and other edible ice, pan masala, and tobacco and manufactured tobacco substitutes cannot opt for the scheme.
எந்த உற்பத்தியாளர்கள் இத்திட்டத்தில் சேர முடியாது?
Ice cream மற்றும் பிற edible ice, Pan Masala, புகையிலை மற்றும் புகையிலைப் பொருட்கள் உற்பத்தியாளர்கள் சேர முடியாது.
8. Which returns does a composition taxpayer file?
Form CMP-08 for quarterly payment of tax and Form GSTR-4 as the annual return.
எந்த ரிட்டர்ன்கள் தாக்கல் செய்ய வேண்டும்?
காலாண்டு வரி செலுத்த Form CMP-08; ஆண்டு ரிட்டர்னாக Form GSTR-4.
9. How do I opt for composition?
New taxpayers opt in Form REG-01. Existing regular taxpayers file Form CMP-02 on the GST portal before the start of the financial year.
கலவைத் திட்டத்தில் எப்படி சேருவது?
புதிய பதிவாளர்கள் Form REG-01-ல் தேர்வு செய்யலாம். ஏற்கனவே regular taxpayer ஆக இருப்பவர்கள் நிதியாண்டு தொடங்குவதற்கு முன் GST portal-ல் Form CMP-02 தாக்கல் செய்ய வேண்டும்.
10. Can I choose Section 10(1) and Section 10(2A) together?
No. Per the GST Portal advisory of 1 Nov 2026, you can select Option A (Section 10(1) categories, multiple allowed) or Option B (Section 10(2A), single selection), but not both together.
Section 10(1), 10(2A) இரண்டையும் சேர்த்து தேர்வு செய்யலாமா?
முடியாது. 1 Nov 2026 GST Portal advisory-ன்படி Option A (பிரிவு 10(1) பிரிவுகள், பல தேர்வு) அல்லது Option B (பிரிவு 10(2A), ஒரே தேர்வு) – இரண்டையும் ஒரே நேரத்தில் தேர்வு செய்ய முடியாது.
11. Who can opt under Section 10(2A), and at what limit and rate?
A registered person not eligible under Section 10(1) and (2), such as a service provider, whose aggregate turnover in the preceding financial year did not exceed Rs 50 lakh. The tax is 6% (3% CGST + 3% SGST).
பிரிவு 10(2A)-ன் கீழ் யார் சேரலாம்; வரம்பு, வரி விகிதம் என்ன?
பிரிவு 10(1), (2)-ன் கீழ் தகுதி இல்லாத, சேவை வழங்குநர் போன்ற பதிவு பெற்ற நபர்; முந்தைய நிதியாண்டு மொத்த விற்றுமுதல் ₹50 லட்சத்துக்கு மிகாமல் இருக்க வேண்டும். வரி 6% (3% CGST + 3% SGST).
12. Can a Section 10(2A) taxpayer claim ITC or collect GST?
No. Composition taxpayers cannot claim ITC on purchases or collect tax from customers.
பிரிவு 10(2A) வரி செலுத்துவோர் ITC எடுக்கவோ GST வசூலிக்கவோ முடியுமா?
முடியாது. Composition வரி செலுத்துவோர் கொள்முதலுக்கு ITC எடுக்கவோ வாடிக்கையாளரிடம் வரி வசூலிக்கவோ முடியாது.
13. I have more than one registration on the same PAN. What should I check?
Check that the category on your existing composition registrations matches the category you select in CMP-02; the portal asks you to make them the same. The turnover limit is checked on the aggregate of all registrations on the PAN.
ஒரே PAN-ல் ஒன்றுக்கு மேற்பட்ட பதிவுகள் இருந்தால் எதைச் சரிபார்க்க வேண்டும்?
ஏற்கனவே உள்ள composition பதிவுகளின் பிரிவும் CMP-02-ல் நீங்கள் தேர்வு செய்யும் பிரிவும் ஒன்றாக இருக்க வேண்டும்; இல்லையெனில் portal ஒன்றாக்கச் சொல்லும். விற்றுமுதல் வரம்பு அந்த PAN-ல் உள்ள அனைத்துப் பதிவுகளின் மொத்தத்தில் சரிபார்க்கப்படும்.
Official Sources
- CGST Act, Section 10 – CBIC
- CGST Rules, Rule 7 – CBIC
- PIB: Notification 14/2019-Central Tax
- GST Portal: Opt for Composition Levy (CMP-02)
- GST Portal Advisory, 1 Nov 2026
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration
