 Phoenix Tax Consultant™ November 20, 2026
Generated an e-invoice and think you don’t need an e-way bill? That is one of the most common GST mistakes – the two documents do completely different jobs.
E-invoice போட்டுவிட்டோம், e-way bill தேவையில்லை என்று நினைக்கிறீர்களா? இது மிகவும் பொதுவான GST தவறு – இரண்டும் முற்றிலும் வேறு வேலைகளைச் செய்கின்றன.
Quick Answer: An e-invoice reports specified B2B invoice details to the IRP and returns an IRN and QR code (mandatory if turnover is Rs 5 crore or more). An e-way bill is needed before moving goods worth more than Rs 50,000 (Rule 138). One cannot replace the other.
Near me: Need e-invoice or e-way bill help near me? Phoenix Tax Consultant™, Tambaram, Chennai – 99403 49819 / 88072 58797.
விரைவு பதில்: E-invoice என்பது B2B invoice விவரங்களை IRP-ல் பதிவு செய்து IRN, QR code பெறுவது (turnover ₹5 கோடி அல்லது அதற்கு மேல் இருந்தால் கட்டாயம்). ₹50,000-க்கு மேல் மதிப்புள்ள பொருட்களை நகர்த்தும் முன் e-way bill தேவை (Rule 138). ஒன்று மற்றொன்றுக்கு மாற்றாகாது.
அருகில் உதவி: E-invoice, e-way bill உதவி near me தேடுகிறீர்களா? தாம்பரம், சென்னை – Phoenix Tax Consultant™: 99403 49819 / 88072 58797.
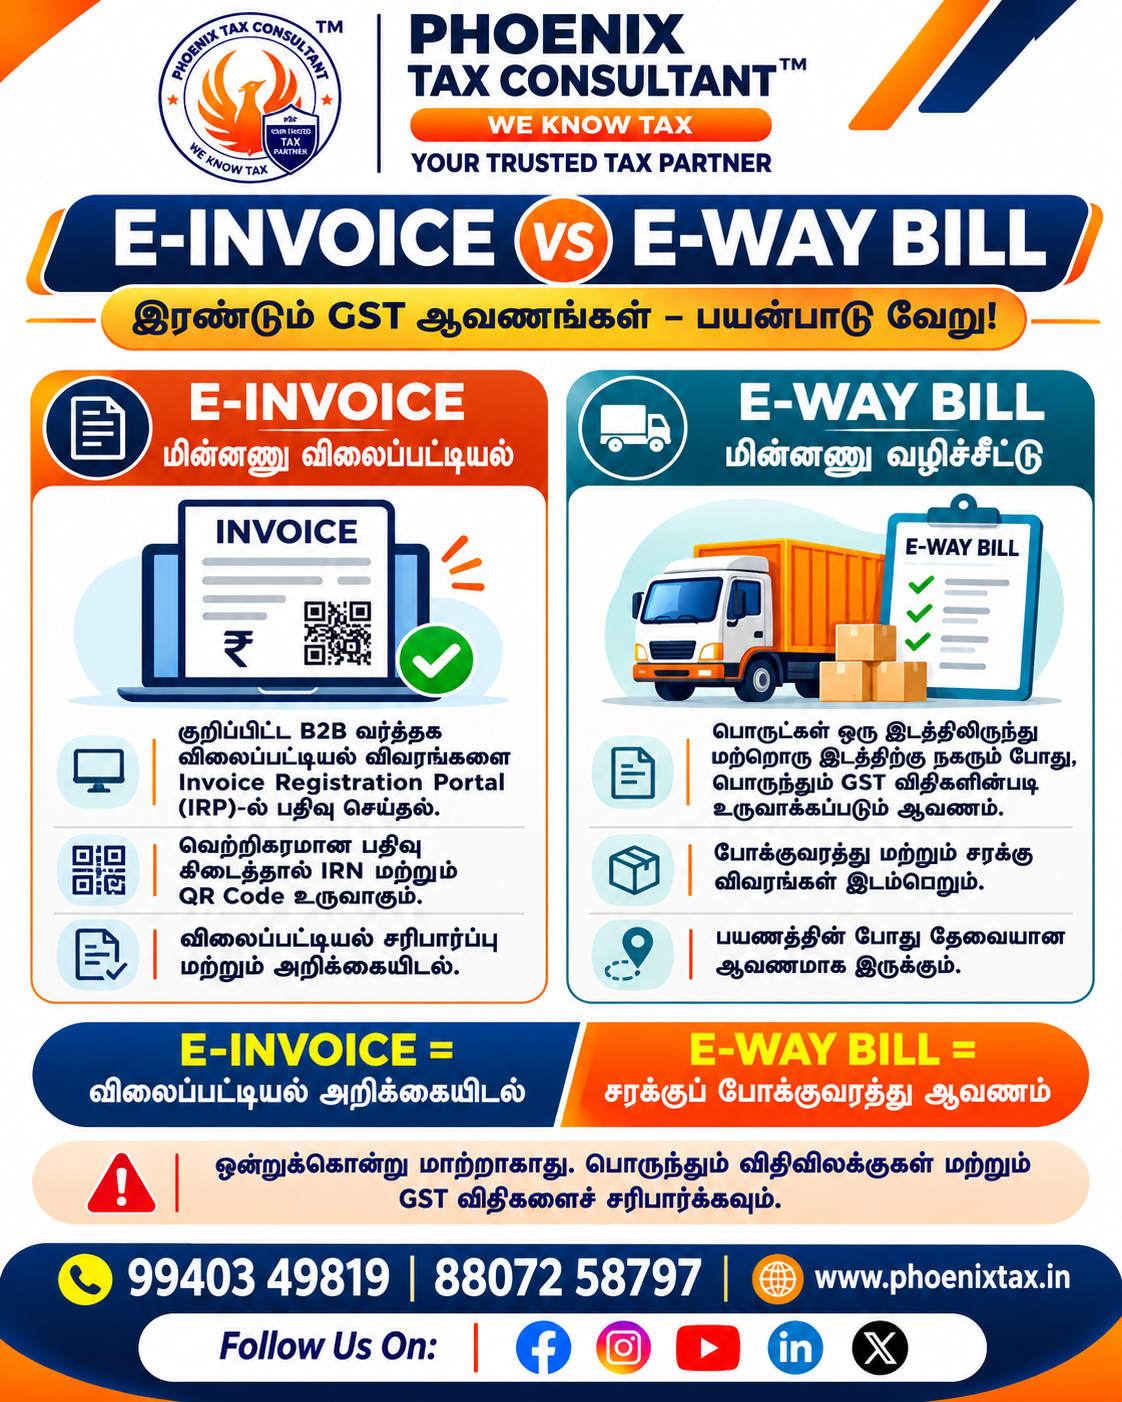
E-Invoice vs E-Way Bill: Side-by-Side
| Point / அம்சம் | E-Invoice | E-Way Bill |
|---|---|---|
| Law / சட்டம் | Rule 48(4), CGST Rules | Section 68 + Rule 138, CGST Rules |
| Purpose / நோக்கம் | Report invoice to IRP / invoice பதிவு | Movement of goods / பொருள் நகர்வு |
| Applies when / எப்போது | Turnover Rs 5 crore or more (from 1.8.2023) | Consignment value above Rs 50,000 |
| Output / கிடைப்பது | IRN + signed QR code | E-way bill number (after Part B) |
| Portal | Invoice Registration Portal (IRP) | E-way bill portal / IRP e-way bill tab |
What Is an E-Invoice?
Under Rule 48(4), notified registered persons prepare their invoice by uploading specified particulars (FORM GST INV-01) to the Invoice Registration Portal and obtaining an IRN (GST e-Invoice FAQ). You still create invoices in your own billing software; the IRP digitally signs the data and adds a QR code. From 1 August 2023 the turnover limit is Rs 5 crore (PIB, GSTN e-invoice guide). Read more: GST e-invoice limit and rules.
E-Invoice என்றால் என்ன?
Rule 48(4)-ன்படி அறிவிக்கப்பட்ட பதிவுபெற்றவர்கள் invoice விவரங்களை (FORM GST INV-01) Invoice Registration Portal-ல் பதிவேற்றி IRN பெற வேண்டும். Invoice-ஐ உங்கள் software-லேயே உருவாக்குவீர்கள்; IRP digital கையொப்பமிட்டு QR code சேர்க்கும். 1 ஆகஸ்ட் 2023 முதல் turnover வரம்பு ₹5 கோடி. மேலும் படிக்க: GST e-invoice வரம்பு, விதிகள்.
What Is an E-Way Bill?
Rule 138(1) requires every registered person who causes movement of goods of consignment value exceeding Rs 50,000 – for supply, for reasons other than supply, or for inward supply from an unregistered person – to furnish Part A of FORM GST EWB-01 before movement (CBIC – Rule 138, CBIC e-way bill FAQ). The e-way bill is generated only after Part B (transport details) is entered. Guides: e-way bill generation, complete e-way bill guide.
E-Way Bill என்றால் என்ன?
Rule 138(1)-ன்படி ₹50,000-க்கு மேல் மதிப்புள்ள பொருட்களை – விற்பனை, விற்பனை அல்லாத காரணம், பதிவில்லாதவரிடமிருந்து வாங்குதல் – எதற்காக நகர்த்தினாலும், நகர்வுக்கு முன் FORM GST EWB-01 Part A நிரப்ப வேண்டும். Part B (போக்குவரத்து விவரம்) சேர்த்த பின்பே e-way bill உருவாகும். வழிகாட்டிகள்: e-way bill உருவாக்குவது, முழு e-way bill வழிகாட்டி.
How the Two Work Together
The IRP and e-way bill systems are linked. If Part A and Part B are given in the e-invoice data, the e-way bill is generated along with the IRN; otherwise Part B must be added later. During transit, the QR code with embedded IRN can be shown electronically instead of a paper invoice (Circular 160/16/2021-GST). E-invoice data also flows into GSTR-1 – see GST return filing in Tambaram, Chennai.
இரண்டும் எப்படி இணைந்து செயல்படுகின்றன?
IRP, e-way bill அமைப்புகள் இணைக்கப்பட்டுள்ளன. E-invoice தரவில் Part A, Part B இரண்டும் இருந்தால் IRN உடன் e-way bill-உம் உருவாகும்; இல்லையெனில் Part B-ஐ பின்னர் சேர்க்க வேண்டும். பயணத்தின்போது IRN உள்ள QR code-ஐ மின்னணு வடிவில் காட்டலாம். E-invoice தரவு GSTR-1-க்கும் செல்லும் – பார்க்க: GST return தாக்கல் – தாம்பரம், சென்னை. புதிய பதிவுக்கு: GST பதிவு.
Who Is Exempt from E-Invoicing?
Even if turnover crosses Rs 5 crore, these entities are exempt from e-invoicing as per Notification 13/2020-Central Tax (as amended) (GST e-invoice exemption manual, e-Invoice FAQ):
- Special Economic Zone (SEZ) units (SEZ developers are not exempt)
- Insurers, banking companies and financial institutions including NBFCs
- Goods Transport Agency (GTA) for transport of goods by road
- Suppliers of passenger transportation service
- Suppliers of admission to cinema exhibition in multiplex screens
- Government departments and local authorities (Notification 23/2021-Central Tax)
E-Invoice விலக்கு யாருக்கு?
Turnover ₹5 கோடியைத் தாண்டினாலும், Notification 13/2020-Central Tax (திருத்தங்களுடன்) படி இவர்களுக்கு e-invoice தேவையில்லை:
- SEZ units (SEZ developers-க்கு விலக்கு இல்லை)
- Insurance நிறுவனங்கள், வங்கிகள், NBFC உள்ளிட்ட நிதி நிறுவனங்கள்
- சாலை வழி சரக்குப் போக்குவரத்து செய்யும் GTA
- பயணிகள் போக்குவரத்து சேவை வழங்குவோர்
- Multiplex திரையரங்க நுழைவுச் சேவை
- அரசுத் துறைகள், உள்ளாட்சி அமைப்புகள் (Notification 23/2021-Central Tax)
Which Documents Need E-Invoice?
GST invoices, credit notes and debit notes for B2B supplies, supplies to SEZ (with or without payment), exports (with or without payment) and deemed exports (GSTN e-invoice guide).
எந்த ஆவணங்களுக்கு e-invoice?
B2B supply, SEZ-க்கான supply (வரியுடன் / வரியின்றி), export (வரியுடன் / வரியின்றி), deemed export ஆகியவற்றுக்கான GST invoice, credit note, debit note.
Important E-Invoice Rules You Must Know
| Rule / விதி | What it means / பொருள் |
|---|---|
| Rule 48(5) | An invoice issued by a notified person without IRN is not treated as an invoice / IRN இல்லாத invoice செல்லாது |
| IRN cancellation | Within 24 hours of reporting; not allowed if the linked e-way bill is active or verified in transit / 24 மணி நேரத்துக்குள் மட்டும் |
| Re-use of number | A cancelled document number cannot be reported again / ரத்தான எண்ணை மீண்டும் பயன்படுத்த முடியாது |
| 30-day limit | From 1 April 2025, AATO Rs 10 crore and above cannot report invoices older than 30 days / ₹10 கோடி+ – 30 நாளுக்கு மேல் பழைய invoice பதிவு செய்ய முடியாது |
| GSTR-1 | E-invoice details auto-populate in GSTR-1 / GSTR-1-ல் தானாக வரும் |
Sources: e-Invoice FAQ, e-Invoice portal, GSTN – e-invoice to GSTR-1. Because e-invoice data flows into GSTR-1, mismatches between your billing software and GSTR-1 should be checked every month.
E-invoice தரவு GSTR-1-க்கு தானாகச் செல்வதால், உங்கள் billing software-க்கும் GSTR-1-க்கும் இடையே உள்ள வேறுபாடுகளை மாதந்தோறும் சரிபார்க்க வேண்டும்.
Step-by-Step: How to Generate an E-Invoice
- Create the invoice in your billing / ERP software (Tally, etc.).
- Generate the JSON in the notified schema (FORM GST INV-01).
- Upload it to any authorised IRP (free of charge).
- IRP validates it and returns IRN + digitally signed QR code.
- Print the QR code on the invoice and share it with the buyer.
- Optionally add transport details to generate the e-way bill at the same time.
படிப்படியாக: E-Invoice உருவாக்குவது எப்படி?
- உங்கள் billing / ERP software-ல் (Tally போன்றவை) invoice உருவாக்குங்கள்.
- அறிவிக்கப்பட்ட schema-வில் (FORM GST INV-01) JSON உருவாக்குங்கள்.
- அங்கீகரிக்கப்பட்ட ஏதேனும் IRP-ல் பதிவேற்றுங்கள் (கட்டணமில்லை).
- IRP சரிபார்த்து IRN, digital கையொப்பமிட்ட QR code தரும்.
- QR code-ஐ invoice-ல் அச்சிட்டு வாங்குபவருக்கு அனுப்புங்கள்.
- போக்குவரத்து விவரம் சேர்த்தால் அதே நேரத்தில் e-way bill-உம் உருவாகும்.
E-Way Bill Validity, Cancellation & Rejection
| Point / அம்சம் | Rule / Detail |
|---|---|
| Validity – normal cargo / சாதாரண சரக்கு | 1 day for every 200 km or part / 200 கி.மீ-க்கு 1 நாள் |
| Validity – Over Dimensional Cargo | 1 day for every 20 km or part / 20 கி.மீ-க்கு 1 நாள் |
| Cancellation / ரத்து | Within 24 hours of generation; not if verified in transit (Rule 138(9)) |
| Rejection by recipient / வாங்குபவர் நிராகரிப்பு | Within 72 hours of generation |
| Extension / நீட்டிப்பு | Online, within 8 hours before or after expiry |
| Inter-State job work | E-way bill needed irrespective of value / மதிப்பைப் பொருட்படுத்தாமல் தேவை |
Validity expires at midnight of the last day. Sources: CBIC – Rule 138, E-way bill portal FAQ, GSTN Welcome Kit. As per the Council’s 2018 recommendation, Part B need not be filled for movement up to 50 km from the consignor’s place to the transporter’s place (CBIC press note).
கடைசி நாளின் நள்ளிரவில் validity முடியும். 2018 GST Council பரிந்துரைப்படி, சரக்கு அனுப்புபவர் இடத்திலிருந்து transporter இடத்துக்கு 50 கி.மீ வரை Part B நிரப்பத் தேவையில்லை.
Step-by-Step: How to Generate an E-Way Bill
- Log in to the e-way bill portal (or use the e-way bill tab in the IRP).
- Fill Part A: GSTIN of supplier and recipient, place of delivery, invoice / challan number and date, HSN code, value.
- Fill Part B: vehicle number (road) or transport document number (rail / air / ship).
- Submit to get the e-way bill number; without Part B you only get a Part-A slip.
- Share the e-way bill number with the transporter before the goods move.
படிப்படியாக: E-Way Bill உருவாக்குவது எப்படி?
- E-way bill portal-ல் (அல்லது IRP-ன் e-way bill tab-ல்) login செய்யுங்கள்.
- Part A: supplier, recipient GSTIN, விநியோக இடம், invoice / challan எண், தேதி, HSN code, மதிப்பு.
- Part B: வாகன எண் (சாலை) அல்லது போக்குவரத்து ஆவண எண் (ரயில் / விமானம் / கப்பல்).
- Submit செய்தால் e-way bill எண் கிடைக்கும்; Part B இல்லையெனில் Part-A slip மட்டும்.
- பொருட்கள் நகரும் முன் e-way bill எண்ணை transporter-க்கு அனுப்புங்கள்.
Practical Example – Tambaram Trader
A Tambaram trader sells goods worth Rs 80,000 to a registered buyer in Bengaluru and sends them by lorry.
- AATO Rs 6 crore: needs an e-invoice (B2B, turnover above Rs 5 crore) and an e-way bill (value above Rs 50,000). Both can be generated together from the IRP.
- AATO Rs 3 crore: no e-invoice, but the e-way bill is still required.
- Goods worth Rs 40,000: no e-way bill under Rule 138(1); e-invoice still applies if turnover is Rs 5 crore or more.
நடைமுறை உதாரணம் – தாம்பரம் வணிகர்
தாம்பரம் வணிகர் ஒருவர் ₹80,000 மதிப்புள்ள பொருட்களை பெங்களூருவில் உள்ள பதிவுபெற்ற வாங்குபவருக்கு லாரியில் அனுப்புகிறார்.
- AATO ₹6 கோடி: e-invoice (B2B, turnover ₹5 கோடிக்கு மேல்), e-way bill (₹50,000-க்கு மேல்) இரண்டும் தேவை; IRP-லேயே இரண்டையும் ஒன்றாக உருவாக்கலாம்.
- AATO ₹3 கோடி: e-invoice தேவையில்லை; ஆனால் e-way bill கட்டாயம்.
- ₹40,000 பொருள்: Rule 138(1)-ன்படி e-way bill தேவையில்லை; turnover ₹5 கோடி அல்லது அதற்கு மேல் இருந்தால் e-invoice தேவை.
Common Mistakes to Avoid
- Thinking an e-invoice replaces the e-way bill (or the reverse).
- Issuing B2B invoices without IRN after crossing Rs 5 crore turnover.
- Generating the e-way bill but leaving Part B blank, so only a Part-A slip exists.
- Missing the 24-hour window to cancel a wrong IRN or e-way bill.
- Letting the e-way bill expire in transit instead of extending it on time.
தவிர்க்க வேண்டிய பொதுவான தவறுகள்
- E-invoice போட்டால் e-way bill தேவையில்லை (அல்லது நேர்மாறாக) என்று நினைப்பது.
- Turnover ₹5 கோடியைத் தாண்டிய பின் IRN இல்லாமல் B2B invoice வழங்குவது.
- Part B நிரப்பாமல் Part-A slip மட்டும் வைத்திருப்பது.
- தவறான IRN / e-way bill-ஐ 24 மணி நேரத்துக்குள் ரத்து செய்யத் தவறுவது.
- பயணத்தின் நடுவே e-way bill காலாவதியாக விடுவது; நேரத்தில் நீட்டிக்காதது.
FAQs / அடிக்கடி கேட்கப்படும் கேள்விகள்
1. What is the difference between e-invoice and e-way bill?
An e-invoice is the reporting of specified invoice details to the Invoice Registration Portal (IRP) to get an IRN and QR code (Rule 48(4)). An e-way bill is a document generated before goods move, under Section 68 and Rule 138 of the CGST Rules.
E-invoice, e-way bill இடையே என்ன வேறுபாடு?
E-invoice என்பது invoice விவரங்களை IRP-ல் பதிவு செய்து IRN, QR code பெறுவது (Rule 48(4)). E-way bill என்பது பொருட்கள் நகரும் முன் உருவாக்கப்படும் ஆவணம் (Section 68, Rule 138).
2. Who must generate an e-invoice?
Taxpayers whose aggregate turnover (PAN-based) in any preceding financial year from 2017-18 is Rs 5 crore or more, from 1 August 2023 (Notification 10/2023-Central Tax).
E-invoice யார் உருவாக்க வேண்டும்?
2017-18 முதல் ஏதேனும் ஒரு நிதியாண்டில் PAN அடிப்படையிலான மொத்த turnover ₹5 கோடி அல்லது அதற்கு மேல் உள்ளவர்கள், 1 ஆகஸ்ட் 2023 முதல் (Notification 10/2023-Central Tax).
3. What is the e-way bill limit?
A registered person who causes movement of goods of consignment value exceeding Rs 50,000 must furnish Part A of FORM GST EWB-01 before the movement starts (Rule 138(1)).
E-way bill limit என்ன?
₹50,000-க்கு மேல் consignment மதிப்புள்ள பொருட்களை நகர்த்தும் பதிவுபெற்ற நபர், நகர்வு தொடங்கும் முன் FORM GST EWB-01 Part A-ஐ நிரப்ப வேண்டும் (Rule 138(1)).
4. Is e-way bill needed for movement other than sale?
Yes. Rule 138(1) covers movement in relation to a supply, for reasons other than supply, and due to inward supply from an unregistered person.
விற்பனை அல்லாத நகர்வுக்கும் e-way bill தேவையா?
ஆம். Supply, supply அல்லாத காரணம், பதிவில்லாதவரிடமிருந்து வரும் inward supply – மூன்றும் Rule 138(1)-ல் அடங்கும்.
5. What do IRN and QR code mean?
On reporting, the IRP returns the e-invoice with a unique Invoice Reference Number (IRN), digitally signs it and adds a QR code.
IRN, QR code என்றால் என்ன?
Invoice-ஐ பதிவு செய்ததும் IRP தனித்துவமான Invoice Reference Number (IRN) கொடுத்து, digital கையொப்பமிட்டு QR code சேர்க்கும்.
6. Does the government portal create my invoice?
No. You still create the invoice in your own billing or ERP software; e-invoicing means reporting it to the IRP.
அரசு portal invoice-ஐ உருவாக்குமா?
இல்லை. Invoice-ஐ உங்கள் billing / ERP software-லேயே உருவாக்குவீர்கள்; அதை IRP-ல் பதிவு செய்வதே e-invoicing.
7. Can an e-way bill be generated from the e-invoice?
Yes. If both Part A and Part B details are given in the e-invoice schema, they are used to generate the e-way bill. If Part B is missing, it must be added in the e-way bill tab of the IRP or on the e-way bill portal.
E-invoice-லிருந்து e-way bill உருவாக்கலாமா?
ஆம். E-invoice schema-வில் Part A, Part B இரண்டும் கொடுத்தால் e-way bill உருவாகும். Part B இல்லையெனில் IRP-ன் e-way bill tab அல்லது e-way bill portal-ல் சேர்க்க வேண்டும்.
8. What is Part A and Part B of an e-way bill?
Part A holds invoice and goods details; Part B holds transport details such as the vehicle number. Without Part B, the system gives only a Part-A slip, not an e-way bill.
E-way bill Part A, Part B என்றால் என்ன?
Part A-ல் invoice, பொருள் விவரங்கள்; Part B-ல் வாகன எண் போன்ற போக்குவரத்து விவரங்கள். Part B இல்லாமல் Part-A slip மட்டும் கிடைக்கும், e-way bill அல்ல.
9. Do I need to carry a physical copy of an e-invoice with goods?
No. Circular 160/16/2021-GST clarifies that the QR code with embedded IRN can be produced electronically instead of the physical copy of the tax invoice.
E-invoice-ன் அச்சுப் பிரதியை பொருட்களுடன் எடுத்துச் செல்ல வேண்டுமா?
தேவையில்லை. IRN உள்ள QR code-ஐ மின்னணு வடிவில் காட்டலாம் என Circular 160/16/2021-GST தெளிவுபடுத்துகிறது.
10. Can one replace the other?
No. They serve different purposes: e-invoice is for invoice reporting, e-way bill is for movement of goods. Check the applicable rules and exemptions for each.
ஒன்றுக்கு பதிலாக மற்றொன்றைப் பயன்படுத்தலாமா?
இல்லை. E-invoice – invoice பதிவு; e-way bill – பொருள் நகர்வு. ஒவ்வொன்றுக்கும் பொருந்தும் விதிகள், விலக்குகளைச் சரிபார்க்கவும்.
11. What is the validity of an e-way bill?
One day for every 200 km or part for normal cargo, and one day for every 20 km or part for Over Dimensional Cargo. Validity expires at midnight of the last day.
E-way bill validity எவ்வளவு?
சாதாரண சரக்குக்கு 200 கி.மீ-க்கு 1 நாள்; Over Dimensional Cargo-க்கு 20 கி.மீ-க்கு 1 நாள். கடைசி நாள் நள்ளிரவில் முடியும்.
12. Who is exempt from e-invoicing?
SEZ units, insurers, banks and financial institutions including NBFCs, GTA, passenger transport service suppliers, multiplex cinema admission suppliers, and government departments and local authorities.
E-invoice-லிருந்து விலக்கு பெற்றவர்கள் யார்?
SEZ units, insurance நிறுவனங்கள், வங்கிகள், NBFC உள்ளிட்ட நிதி நிறுவனங்கள், GTA, பயணிகள் போக்குவரத்து, multiplex திரையரங்க நுழைவு, அரசுத் துறைகள் மற்றும் உள்ளாட்சி அமைப்புகள்.
Official Sources
- GST e-Invoice Portal – FAQs
- GST e-Invoice – Exemption manual
- E-way bill portal – FAQs
- CBIC – CGST Rules, Rule 138
- CBIC – E-way bill FAQs
- CBIC – Circular 160/16/2021-GST
- PIB – e-invoicing threshold Rs 5 crore
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration