 Phoenix Tax Consultant™ November 18, 2026
Paying a home loan and filing under the new tax regime? Your self-occupied house gets zero interest deduction – but a rented house still does, with no upper limit. With the Income-tax Act, 2025 in force for Tax Year 2026-27, the old “Section 24(b)” now sits in Section 22(1)(b). Here is what actually changes for you.
Home loan கட்டுகிறீர்களா? New tax regime-ல் சொந்த வீட்டுக்கு (self-occupied) interest deduction கிடையாது – ஆனால் வாடகைக்கு விட்ட வீட்டுக்கு வரம்பில்லாமல் கிடைக்கும்! Income-tax Act, 2025-ல் பழைய “Section 24(b)” இப்போது Section 22(1)(b). Tax Year 2026-27-க்கு என்ன மாறியது என்று பார்ப்போம்.
Quick answer | விரைவான பதில்
Under the new tax regime (Section 202, Income-tax Act, 2025), home loan interest deduction is not allowed for a self-occupied house. For a let-out (rented) house, actual interest on the loan is deductible under Section 22(1)(b) with no monetary ceiling, plus a 30% standard deduction on annual value. But any house property loss cannot be set off against salary or other income, and cannot be carried forward. Need help with home loan tax benefit near me? Phoenix Tax Consultant™, Tambaram, Chennai files your ITR correctly.
New tax regime-ல் (Section 202) சொந்தமாக வசிக்கும் வீட்டுக்கு home loan interest deduction இல்லை. வாடகைக்கு விட்ட வீட்டுக்கு Section 22(1)(b) படி முழு interest-ஐ வரம்பின்றி கழிக்கலாம்; annual value-ல் 30% standard deduction-உம் உண்டு. ஆனால் house property loss-ஐ சம்பளம் போன்ற வேறு வருமானத்துடன் set off செய்யவோ, அடுத்த ஆண்டுக்கு carry forward செய்யவோ முடியாது. அருகில் (near me) உதவி வேண்டுமா? Tambaram, Chennai-ல் Phoenix Tax Consultant™ உங்கள் ITR-ஐ சரியாக file செய்யும்.
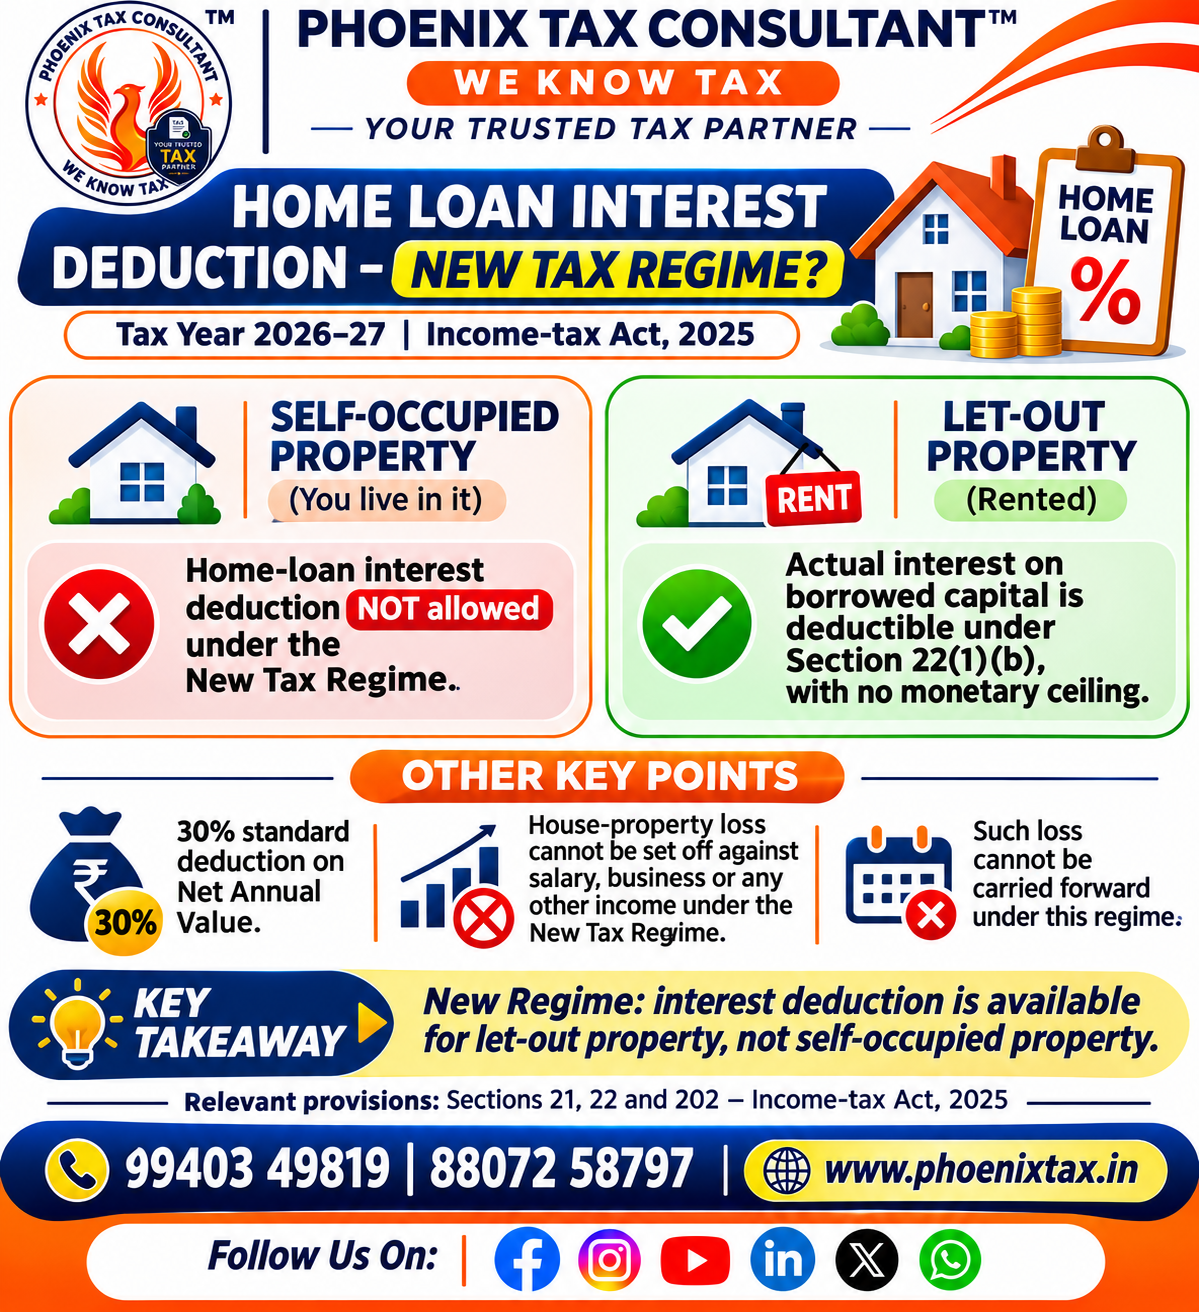
Home loan interest deduction in new tax regime – the rule
Section 202 of the Income-tax Act, 2025 lists the deductions you give up when you choose the new tax regime. One of them is the interest deduction under Section 22(1)(b) for properties referred to in Section 21(6) – that is, a house you live in yourself. So a salaried person in the new regime gets no tax benefit for home loan interest on their own home.
Income-tax Act, 2025-ன் Section 202, new tax regime-ஐ தேர்வு செய்பவர்களுக்கு கிடைக்காத deductions-ஐ பட்டியலிடுகிறது. அதில் Section 21(6)-ல் குறிப்பிடப்பட்ட (நீங்களே வசிக்கும்) வீட்டுக்கான Section 22(1)(b) interest deduction-உம் ஒன்று. எனவே new regime-ல் உள்ளவர்களுக்கு சொந்த வீட்டு home loan interest-க்கு வரிச் சலுகை இல்லை.
Self-occupied vs let-out property – new regime at a glance
| Point | Self-occupied (you live in it) | Let-out (rented) |
|---|---|---|
| Home loan interest deduction – Sec 22(1)(b) | ❌ Not allowed | ✅ Actual interest, no ceiling |
| 30% standard deduction – Sec 22(1)(a) | Not relevant | ✅ 30% of annual value |
| Set off house property loss against other income | ❌ No | ❌ No |
| Carry forward of that loss | ❌ No | ❌ No |
சுருக்கமாக: சொந்த வீடு – interest deduction இல்லை. வாடகை வீடு – முழு interest + 30% standard deduction உண்டு. இரண்டிலும் loss-ஐ வேறு வருமானத்துடன் set off அல்லது carry forward செய்ய முடியாது.
Let-out property: interest with no upper limit
Section 22(1)(b) allows the interest payable on capital borrowed to acquire, construct, repair, renew or reconstruct the property. The ₹2,00,000 cap in Section 22(2) applies only to properties under Section 21(6) (self-occupied). So for a rented house, the full interest is deductible from the rental income, after the 30% standard deduction under Section 22(1)(a).
வீடு வாங்க, கட்ட, பழுது பார்க்க அல்லது புதுப்பிக்க வாங்கிய கடனின் interest-ஐ Section 22(1)(b) அனுமதிக்கிறது. Section 22(2)-ல் உள்ள ₹2,00,000 வரம்பு சொந்த வீட்டுக்கு (Section 21(6)) மட்டுமே. எனவே வாடகை வீட்டுக்கு 30% standard deduction-க்குப் பிறகு முழு interest-ஐயும் கழிக்கலாம்.
Example: what happens to the loss?
| Item (illustration) | Amount (₹) |
|---|---|
| Annual value of let-out house | 3,00,000 |
| Less: 30% standard deduction | (90,000) |
| Less: home loan interest | (2,50,000) |
| Loss from house property | (40,000) |
In the new regime this ₹40,000 loss cannot reduce your salary or business income, and it cannot be carried forward – it simply lapses. In the old regime, a house property loss can be set off against other heads up to ₹2,00,000 and the balance carried forward for up to eight tax years.
New regime-ல் இந்த ₹40,000 loss உங்கள் சம்பள வருமானத்தைக் குறைக்காது; அடுத்த ஆண்டுக்கும் செல்லாது – அது அப்படியே போய்விடும். Old regime-ல் ₹2,00,000 வரை வேறு வருமானத்துடன் set off செய்து, மீதியை 8 tax years வரை carry forward செய்யலாம்.
Old regime vs new regime – which is better for home loan borrowers?
If you live in your own house and pay large home loan interest, the old regime still gives up to ₹2,00,000 deduction under Section 22(2), subject to its conditions. The new regime gives lower slab rates but no such deduction. Compare your total tax under both before choosing – our tax-saving guide and Section 80C explainer help you work it out.
சொந்த வீட்டில் வசித்து அதிக interest கட்டுபவர்களுக்கு old regime-ல் Section 22(2) படி ₹2,00,000 வரை deduction உண்டு (நிபந்தனைகளுக்கு உட்பட்டு). New regime-ல் slab rate குறைவு, ஆனால் இந்த deduction இல்லை. இரண்டிலும் மொத்த வரியைக் கணக்கிட்டு பிறகு முடிவு செய்யுங்கள்.
Section 24(b) is now Section 22(1)(b)
Many people still search for “Section 24(b)”. Under the new Income-tax Act, 2025, the deductions from income from house property – 30% of annual value and interest on borrowed capital – are in Section 22. The new tax regime is in Section 202.
பலர் இன்னும் “Section 24(b)” என்று தேடுகிறார்கள். Income-tax Act, 2025-ல் house property deductions (30% மற்றும் interest) Section 22-ல் உள்ளன; new tax regime Section 202-ல் உள்ளது.
Home loan tax benefit help near me – Tambaram, Chennai
Phoenix Tax Consultant™ helps salaried employees, landlords and NRIs in Tambaram, Chromepet, Pallavaram, Selaiyur, Perungalathur and across Chennai choose the right regime and claim house property deductions correctly. We handle ITR filing in Tambaram, Chennai, including ITR-2 for house property income.
Tambaram, Chromepet, Pallavaram, Selaiyur, Perungalathur மற்றும் Chennai முழுவதும் சம்பளதாரர்கள், வீட்டு உரிமையாளர்கள், NRI-களுக்கு சரியான regime தேர்வு, house property deduction claim, ITR filing செய்து தருகிறோம். அழைக்க: 99403 49819 / 88072 58797.
FAQs / அடிக்கடி கேட்கப்படும் கேள்விகள்
Is home loan interest deduction allowed in the new tax regime?
Not for a self-occupied house. Section 202 of the Income-tax Act, 2025 excludes the Section 22(1)(b) interest deduction for properties under Section 21(6). For a let-out house, actual interest is deductible.
New tax regime-ல் home loan interest deduction உண்டா?
சொந்தமாக வசிக்கும் வீட்டுக்கு இல்லை. Section 21(6) வீடுகளுக்கான Section 22(1)(b) deduction-ஐ Section 202 விலக்குகிறது. வாடகை வீட்டுக்கு முழு interest கழிக்கலாம்.
What is Section 24(b) called under the Income-tax Act, 2025?
The interest deduction on borrowed capital for house property is in Section 22(1)(b) of the Income-tax Act, 2025, and the 30% standard deduction is in Section 22(1)(a).
Income-tax Act, 2025-ல் Section 24(b) என்ன ஆனது?
House property கடன் interest deduction இப்போது Section 22(1)(b); 30% standard deduction Section 22(1)(a).
Is there a limit on home loan interest for a let-out property in the new regime?
No monetary ceiling. The ₹2,00,000 limit in Section 22(2) applies only to self-occupied properties under Section 21(6).
New regime-ல் வாடகை வீட்டுக்கு interest வரம்பு உண்டா?
பண வரம்பு இல்லை. Section 22(2)-ன் ₹2,00,000 வரம்பு சொந்த வீட்டுக்கு (Section 21(6)) மட்டுமே.
Can I set off house property loss against salary in the new regime?
No. Section 202 requires total income to be computed without setting off any loss under the head Income from house property against any other head.
New regime-ல் house property loss-ஐ சம்பளத்துடன் set off செய்யலாமா?
முடியாது. House property loss-ஐ வேறு எந்த வருமானத் தலைப்புடனும் set off செய்யக்கூடாது என்று Section 202 சொல்கிறது.
Can that house property loss be carried forward?
No. Under Section 202(3) such loss is deemed to have been given full effect, and no deduction is allowed for it in any later year.
அந்த loss-ஐ அடுத்த ஆண்டுக்கு carry forward செய்யலாமா?
முடியாது. Section 202(3) படி அது முழுமையாக பயன்படுத்தப்பட்டதாகக் கருதப்படும்; பின்வரும் ஆண்டுகளில் deduction கிடையாது.
Is the 30% standard deduction available in the new regime?
Yes. Section 22(1)(a) allows 30% of the annual value of a let-out property; it is not among the deductions excluded by Section 202.
New regime-ல் 30% standard deduction உண்டா?
ஆம். வாடகை வீட்டின் annual value-ல் 30% Section 22(1)(a) படி கிடைக்கும்; Section 202 அதை விலக்கவில்லை.
How much home loan interest can I claim in the old regime for my own house?
Up to ₹2,00,000 under Section 22(2), if the house was acquired or constructed with the loan within five years from the end of the tax year of borrowing and you have the lender’s interest certificate.
Old regime-ல் சொந்த வீட்டுக்கு எவ்வளவு interest claim செய்யலாம்?
Section 22(2) படி ₹2,00,000 வரை – கடன் வாங்கிய tax year முடிவிலிருந்து 5 ஆண்டுக்குள் வீடு வாங்கப்பட்டு/கட்டப்பட்டு, lender-ன் interest certificate இருந்தால்.
Which regime is better if I have a home loan?
It depends on your income and deductions. If you live in your own house with high interest, compare tax under both regimes; the new regime gives no interest deduction for that house.
Home loan இருந்தால் எந்த regime நல்லது?
உங்கள் வருமானம், deductions பொறுத்தது. சொந்த வீட்டுக்கு அதிக interest இருந்தால் இரண்டு regime-லும் வரியைக் கணக்கிட்டுப் பாருங்கள்.
Which law applies for Tax Year 2026-27?
The Income-tax Act, 2025 – house property deductions are in Section 22 and the new tax regime is in Section 202.
Tax Year 2026-27-க்கு எந்த சட்டம்?
Income-tax Act, 2025 – house property deductions Section 22-ல், new tax regime Section 202-ல்.
Can Phoenix Tax Consultant™ help with home loan tax benefit near me in Tambaram, Chennai?
Yes. Our Tambaram, Chennai team compares both regimes, computes house property income and files your ITR. Call 99403 49819 / 88072 58797.
Tambaram, Chennai-ல் Phoenix Tax Consultant™ உதவுவார்களா?
ஆம். இரண்டு regime-ஐயும் ஒப்பிட்டு, house property வருமானம் கணக்கிட்டு ITR file செய்கிறோம். அழைக்க: 99403 49819 / 88072 58797.
Official Sources
- Income Tax Department – Section 22, Income-tax Act, 2025
- Income Tax Department – Section 202 (new tax regime)
- Income-tax Act, 2025 (as amended by Finance Act, 2026)
- e-Filing portal – Set off / carry forward of losses FAQs
- e-Filing portal – Objective and scope of the new Act
Need Help? | உதவி வேண்டுமா?
Contact Phoenix Tax Consultant™ today for hassle-free help. | எளிதான சேவைக்கு இன்றே தொடர்பு கொள்ளுங்கள்.
Call 9940349819 | Call 8807258797 | jai@phoenixtax.in
Phoenix Tax Consultant™, West Tambaram, Chennai 600045
Related services: Income Tax Return Filing | GST Registration | MSME Udyam Registration